I received a windfall from the proceeds of a Great Eastern Endowment Plan - Maxsave Enhanced Savings purchased 10 years ago.
Friday, June 24, 2022
Boost to War Chest from Endowment Plan Proceeds
I received a windfall from the proceeds of a Great Eastern Endowment Plan - Maxsave Enhanced Savings purchased 10 years ago.
Saturday, June 18, 2022
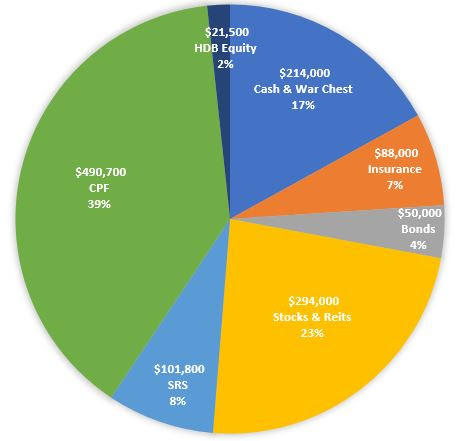
Net Worth Update June 2022
S$1.27m
It is time for another monthly net worth update.
Having collected my June 2022 salary, May 2022 CPF contributions and more dividends from my SGX income portfolio, I paid off all my credit card liabilities, bills and income tax.
My net worth increases to $1.27m.
I have completed SRS contribution of $15.3k, $8k RSTU of CPF SA account and $8k RSTU of my mum's CPF RA account for 2022.
I have subscribed to Astrea 7 PE Class A-1 bond through IPO and was allocated $9k.
In the US stock market, I continue to increase my investments in growth businesses such as Alphabet Inc., and Palantir, while also monitoring other tech companies such as Microsoft, Amazon Inc. and banks such as Citigroup and Bank of America.
On the local SGX front, I remain on the lookout for the out-of-favour high quality Frasers and Mapletree Reits and ready to pounce on them to increase my investments for more dividends in future.
I have also witnessed the crash of crypto currencies and have written off around $500 of my exposure to Crypto in Cronos tokens from staking in Crypto.com and some other altcoins like Cardano, Nano and Holo.
The next half of this year 2022 remains challenging and unpredictable. Immense inflation has triggered the Fed to raise interest rates by 0.75%. Global supply chain crunch, rising oil prices and the Ukraine war have caused the prices of food and necessities to surge. The stock markets have entered bear territories can seem more likely to tank further than rebound strongly.
In such monetary environment, Cash is King! We should demand higher yields from banks, bonds, Reits and be more prudent with spending our monies.
Life is returning back to normalcy with resumption of physical meetings and events. Travelling has also resumed back to pre-pandemic days with more countries reopening their border.
Life is still great. Ignore the noises. Stay focused. Remain on track. Be greedy when others are fearful. We will get to our goals and dreams eventually.
Tuesday, June 07, 2022
Contribution to Nation Building By Paying Taxman
I received an SMS from the taxman notifying my liability of income tax due early next month.
I logged in to IRAS portal to verify and confirm the amount and due date.
Tuesday, May 31, 2022
Portfolio Update May 2022
Today is the last day of May 2022 for me to review my investment portfolios.
The stock markets have remained volatile engulfed under the immense noises engulfing Fed tapering, interest rates hikes, inflation fears, recession fears, Omicron variant fears, rise of US Treasury yields, Ukraine war, poor company quarterly results and so on.
Whether it will stay as a bear market or merely just a correction remains uncertain. There are emerging signs of stabilization and rebound. Nevertheless, time in the market always beats timing the market. Every market tank leads to a rebound, stronger than ever before.
The stock market always and only goes up, at least for the S&P 500 or Dow Jones. SGX and HSI have no guarantee of such trend though.
I remain invested and continue to hunt for income-producing assets and growth businesses in the coming few weeks, for the long-term.
My SGX Income Portfolio value plummets to $271.4k from $283.2k last month mainly due to the rather heavy correction of S-Reits to reflect the impact of interest rate hikes.
1. Assigned 100 shares of Palantir Technology Inc. at $20 from a PLTR220819 put option with $20 strike price on Moomoo.
2. Subscribed $9,000 of Astrea 7 PE Class A-1 bonds successfully. My bonds are not reflected and tracked in SGX Income Portfolio.
Portfolio Dividends
1. Received $114 of dividends from Savings Bonds on 1 May.
2. Received $157.50 of dividends from Wilmar on 6 May in SRS account.
3. Received $72 of dividends from Sembcorp Industries on 10 May.
4. Received $470 of dividends from ST Engineering on 10 May in SRS account.
5. Received $370.20 of dividends from UOB on 13 May.
6. Received $960.12 of dividends from OCBC on 20 May in SRS account.
7. Received $42 of dividends from OUE on 26 May.
8. Received $105 of dividends from Comfortdelgro on 27 May in SRS account.
9. Received $184.08 of dividends from Frasers Centrepoint Trust on 30 May.
10. Received $119.55 of dividends from Suntec Reit on 30 May.
SGX Income Portfolio
SRS Ultra Long-Term Portfolio
Thank you for reading. As always, stay safe and remain strong.
Saturday, May 28, 2022
5 Reasons Why I Topped Up CPF Retirement Account of Parent
I just topped up $8k into my mum's CPF Retirement Account today.
Let me reiterate 5 reasons why I did so instead of giving cash.
1. Tax Relief
For selfish reason, I would like to enjoy tax relief of up to $8k per calendar year for topping up my parent's CPF Retirement Account under the Retirement Sum Top Up (RSTU) scheme.
Assuming my tax bracket is at 7%, a relief of $8k will save me $560 of taxes in cash, which is enough to eat more than 100 plates of $4 cai png (vegetables rice) at the coffeeshop.
The tax relief is also applicable to family members such as parents-in-law, grandparents, grandparents-in-law, siblings and spouse.
2. Compounding growth at 4%
In today's high inflation environment, the value of cash is also stifled by relatively low interest rates offered by banks' savings accounts.
CPF Retirement Account yields at least 4% and up to 6% for senior folks risk-free and guaranteed by the Singapore Government. Monies growing at compounded rate of at least 4% will double in 20 years hence, by leaving cash in CPF RA account, they will grow much faster than inflation rate to preserve and uphold its real value.
3. CPF Life
In order to qualify for CPF Life, one need to have at least $60k in their CPF retirement savings before reaching 65 years old. I am helping my mum to boost her CPF retirement savings to qualify for CPF Life as she does not have active income and CPF contributions.
CPF Life offers payouts perpetually for life but is a debatable subject because its pros and cons varied across individuals' opinions. If one's CPF RA does not have $60k before reaching 65 years old, then he or her will only rely on Retirement Savings scheme to draw down their CPF savings till it is depleted.
Having at least $60k in CPF RA will offer extra choice of being able to qualify for CPF Life scheme to enjoy perpetual monthly payouts.
4. Matched Retirement Savings Scheme
Under the Matched Retirement Savings Scheme (MRSS), the Government will match every dollar of cash top-ups made to the Retirement Account of eligible members up to a cap of $600, which can amount to $3,000 over 5 years. To be eligible, the person has to be aged between 55 and 70, has a CPF RA of less than the current Basic Retirement Sum of $96k, has average monthly income of less than $4k, live in a property with annual value less than $13k and not own any private property.
By topping up at least $600 to a qualified family member's CPF RA account, we can milk the $600 of free money from the Government every year.
5. CPF is like golden ATM for senior citizens
For senior folks close to reaching the 55 year old and 65 year old milestones of being able to touch their CPF monies, their CPF accounts are like golden ATM that offer high interest rates for "withdrawable" cash with the click of a button. This is unlike younger folks who could only stare at their CPF balances as numbers. Hence, the concept of 1M65 is indeed beneficial and practical to people who could really live beyond 50s or 60s and on the brink of drawing down cash from their CPF balances. People who lived past 50 years old should try to pump more monies into their CPF accounts, by all means, in order to reap the risk-free guaranteed returns on their monies.
In conclusion, I top up my parent's CPF RA account with cash instead of giving cash, in order to maximise the value of money. For the $8k topped up, I can enjoy $560 of tax savings myself, let my mum earn at least $280 of CPF interests for 2022 and attract another matched $600 from the Government. In addition, there is compounding effect from future years' interests and being eligible to qualify for CPF Life for perpetual monthly income payouts. Overall, I feel that it is an awesome deal.
Thursday, May 26, 2022
My Allocation of Astrea 7 Class A-1 PE Bond
Thanks for reading.
Tuesday, May 24, 2022
Applied Astrea 7 Class A-1 PE Bond
I have applied $11k of Astrea 7 PE Class A-1 bonds via OCBC Internet Banking today.
Wishing myself and all applicants good luck!
Sunday, May 15, 2022
5 Lessons Learnt From Crypto Crash
Crypto currencies have crashed hard for the past week.
Most spectacularly, the value of Terra LUNA was wiped out 99.99% to become almost worthless.
Bitcoin value was shed more than half and Ethereum dropped by more than 30%.
Luckily, my exposure to crypto currencies was only less than $600. It was a new venture or rather an experiment by staking $500 worth of Cronos token for the Ruby Red Crypto.com debit card which gave 2% (Reduced to 1%) and free Spotify reimbursement. I also bought some Nano, Holo, Ripple, Cardono and Matic for fun. I do not intend to buy more nor sell them. Will keep all my crypto in cold storage.
With a conservative mindset, I have been sceptical on crypto currencies for a long time and only dabbled late last year after almost a decade of inception by Bitcoin.
Let me share 5 lessons learnt from this episode of crypto crash.
1. Portfolio Allocation is very Important
We would have suffered tremendous losses if we have allocated a relatively huge proportion of our assets to crypto currencies or worst case, LUNA.
If we manage our risks by exposing our investments in Bitcoin or other crypto currencies to at most 5% or 10% of our net worth or assets, we should be fine.
2. Cryptocurrencies have no Underlying Backing
Unlike a country's currency which is backed by its reserves or gold. Crypto currencies are purely driven by demand and supply of traders, investors and largely driven by fear and greed.
A company stock is almost the same as crypto but a company's equity can be backed by its fundamentals in terms of revenue, cashflow or profit generating ability of a business.
3. High Risk High Returns
The reason for high Annual Percentage Yield for crypto through staking or huge capital gains is due to its high risks.
Higher returns compensate for the great amount of risks that a crypto investor bear when he or her stakes their crypto on various crypto exchange platforms which again present more uncertainties and risks. Regulatory, systematic, unsystematic, forex, technology, political, corporate risks just to name some.
The same thing happens to bonds and funds whereby junk bonds and funds of developing economies present much greater yields than stable triple A rated bonds or funds comprising top quality blue chips businesses from US.
High risks translate into high returns, which at the same time means greater volatility and could present high potential losses.
4. Invest money that we could afford to lose
Similar to investment in stocks or buying lottery, we should only invest or punt using our spare cash or war chest that we do not need for our daily expenses.
We should always avoid using margin or leverage or borrow money to dabble in high risk financial instruments like stocks, bonds, options, derivatives and crypto currencies.
5. No Fear No Greed
Since more than 2 million years ago, humans were always irrational with emotions and usually made decisions largely driven by fear or greed.
Wars, fighting, looting, crimes, were all driven by greed. The inventions of weapons, cannons, guns, defences, castles, barricades were all due to fear and lack of sense of security.
Greed results in fear of missing out or FOMO thereby chasing higher and higher prices leasing to people buying crypto currencies at inflated prices.
Fear results in people running for exits and cutting losses to get back their money when shit hits the fan.
Cryptocurrencies were invented for humans with great intentions to resolve limitations of traditional currencies and for anyone on earth to own a stake of the Internet, make secured digital payments, store digital money safely, beat inflation in this digital world.
However, just like any financial asset, Cryptocurrencies become a great digital asset for speculative trading and punting other than long-term investment.
Every crisis is an opportunity and perhaps a great wake up call to budding and seasoned investors and traders of crypto.
Saturday, May 14, 2022
Net Worth Update May 2022 | Growth Stagnated
S$1.26m
It is middle of the May month for another typical net worth update.
Having collected my May 2022 salary, Apr 2022 CPF contributions and some dividends from my SGX income portfolio for this quarter, I paid off all my credit card liabilities and bills.
Being debt free allows me to own a peace of mind to sleep soundly.
The stock markets have crashed due to the immense noises of recession fears, interest rate hikes, commodities prices spike, inflation, pandemic, war etc. and wiped out more than $10k of my net worth.
As a result, my net worth stagnates at $1.26m.
I have completed SRS contribution of $15.3k, RSTU of CPF SA account of $8k and plan to start top up my mum's CPF RA account.
I have transferred a matured fixed deposit with UOB to OCBC at 1.28% p.a. and tempted to subscribe the Jun 2022 tranche of the Singapore Savings Bond which offers around 2.5% p.a. yield for the next 10 years.
I have another fixed deposit with UOB maturing this month and an Great Eastern endowment maturing next month and I may use those proceeds to subscribe for Singapore Savings Bond.
In the US stock market, I continue to increase my investments in growth businesses such as Alphabet Inc., and Palantir, while also monitoring other tech companies such as Microsoft, Amazon Inc. and banks such as Citigroup and Bank of America.
On the local SGX front, I remain on the lookout for the out-of-favour high quality Frasers and Mapletree Reits and ready to pounce on them to increase my investments for more dividends in future.
As my priorities are on the US and SG stock markets, I do not have plan to catch the falling knives presented by the likes of Chinese ATM (Alibaba, Tencent and Meituan) yet.
I have also witnessed the crash of crypto currencies and experienced a paper loss of a meagre $300 from my exposure to Cronos tokens from staking in Crypto.com. I have written off around $500 of my investment in Crypto and excluded them from my net worth computation.
The coming months in this year 2022 remains challenging and predictable. Immense inflation has caused prices of food and necessities to surge. The stock markets stay volatile and could test lower supports into bear territories or could rebound strongly. In this endemic tropical island, we get to live our lives normally and gradually see normalcy returns. Borders with other countries have reopened and the passport waiting time is around 6 weeks. It is now time to regain back the lost freedom for the past 2 years.
Ignore the noises. Stay focused. Remain on track. Be greedy when others are fearful. We will get to our goals and dreams eventually.
Saturday, April 30, 2022
Portfolio Update Apr 2022
April 2022 has come to an end. It is time for me to review my investment portfolios.
The stock markets have tanked and remained volatile engulfed under the immense noises engulfing Fed tapering, interest rates hikes, inflation fears, recession fears, Omicron variant fears, rise of US Treasury yields, Ukraine war, poor company quarterly results and so on.
Whether it is the beginning of a bear market or just a correction remains uncertain. Nevertheless, time in the market always beats timing the market. Every market tank leads to a rebound, stronger than ever before.
The stock market always and only goes up, at least for the S&P 500 or Dow Jones. SGX and HSI have no guarantee of such trend though.
I remain invested and continue to hunt for income-producing assets and growth businesses in the coming few weeks, for the long-term.
My SGX Income Portfolio value inches up to $283.2k from $282k last month mainly due to recovery of tourism related Ascott Reit and Suntec Reit.
1. Added 1 share of Alphabet Inc. at $2580 and another share at $2278 on Tiger Broker.
2. Added 90 shares of Palantir Technology Inc. at $10.88 on Moomoo.
3. Nibbled 0.1 share of Amazon.com, Inc at $2572 on Syfe Trade.
Portfolio Dividends
1. Received $98 of dividends from Savings Bonds on 1 Apr.
2. Received US$1.88 of dividends from TSMC on 15 Apr.
SGX Income Portfolio
SRS Ultra Long-Term Portfolio
Thank you for reading. As always, stay safe and remain strong.
Friday, April 29, 2022
Nibbled Amazon.com, Inc. (NASDAQ: AMZN)
The share price of Amazon.com, Inc. (NASDAQ: AMZN) tanked by more than 10% today after reporting a loss of US$3.8 billion in 1Q 2022 compared to profits of US$7.7 billion in 1Q 2021, registering slow growth and falling short of market's expectations.
What worries investors are the free cash outflow of US$18.6 billion for the trailing 12 months compared to free cash inflow of US$26.4 billion for the trailing 12 months ending 31 Mar 2021.
I am loving this great opportunity as Amazon is another great big tech business that I have been eyeing for a long time.
Its dominance in the e-commerce world, cloud computing space, video streaming and advertisement business gave itself a strong economic moat unrivalled by most companies. I believe Amazon will thrive and continue growing at least for the next decade. Its investments into new computing infrastructure and warehouse distribution systems to grow its dominance in AWS cloud service provider arena and e-commerce supply chain result in great negative cashflow for the past year but such investments will definitely generate hefty recurrent cashflows in the long-run.
Using Syfe Trade platform, I nibbled 0.1 share of Amazon to initiate a tiny position.
Wednesday, April 27, 2022
Alphabet Inc. (NASDAQ:GOOGL) tanked. Added more.
Added Palantir (NYSE:PLTR)
I first nibbled 10 shares of Palantir Technology Inc. (NYSE:PLTR) at $22.65 in Dec 2021 using free money collected from selling put options.
I am also holding 2 put option contracts committing to buy 200 shares of Palantir at $20 by 19 Aug 2022. I will most likely be rolling them down to next year.
Yesterday I placed an order to buy 90 shares of Palantir at $10.88 and it was filled this morning at 4am.
I now hold 100 shares of Palantir and can sell call options to collect premium soon!
Palantir has drawn flak from its secrecy data analytics business dealing with privacy and data from government and intelligent agencies. Despite enjoying growth in revenue and business, Palantir is not yet profitable and is burning cash due to facing rising costs and overheads. This is like catching a falling knife.
However, I believe in the growth prospects of the artificial intelligence and data mining software tools provided by Palantir which are trusted by the U.S government and becoming increasingly valuable in the commercial world. The recurring income streams from government contracts with U.S Special Operations Command, National Nuclear Safety Administration, U.S Space Force Command, etc. have provided stability to its bottom line. Its commercial growth accelerated last year and is at a faster pace than its conservative government business. This is a make or break business prospect in the long-term and I have confidence in the reward-to-risk ratio and decided to allocate at most 1% of my net worth in this company.
Palantir is a unique business with a strong economic moat offering unique data analytics solutions with sustainable competition edge. Its Gotham software allows U.S military and law enforcement agencies to maintain peace and order for not just U.S but also the world. Its data mining capabilities allowed the hiding location of terrorist Osama Bin Laden to be identified decades ago. Early this year, Palantir collaborated with Hyundai Heavy Industries Group to use data analytics to improve and streamline shipbuilding, offshore engineering, energy and industrial engineering processes. What's more to come? The latest rumours in the commercial space involve potential collaboration between Google and Palantir on their cloud platform and Foundry solutions respectively.
Thanks for reading. As always, stay safe and remain strong.
Monday, April 25, 2022
Money is Cash or Numbers?
When was the last time you touched a one hundred dollar note?
In today's digital payment world, often we only see numbers of money in our bank account balances from Internet banking or withdraw at most one hundred dollars of cash from ATM for daily expenditure.
Today I withdrew wads of hundred dollar notes from UOB as my fixed deposit matured. To be exact, more than 1000 pieces as one thousand notes are no longer in circulation.
The renewal rate in UOB was only 0.7% p.a. which is too low and greatly erodes my money due to inflation. Initially I renewed the fixed deposit for a paltry interest sum of $679 for 10 months with $115k.
However, after some research I decided to cancel the fixed deposit with UOB and withdraw full amount in cash.
I brought the cash over to OCBC as fresh funds to enjoy 1.28% p.a. interest rate for 24 months which is much more attractive.
Even though it is not financially wise to hoard too much cash away, the conservative self in me still prefers to keep cash in the banks first, to give myself some psychological support before I decide to invest more of my "new" monies in the stock markets.
There it is. My new fixed deposit with OCBC.
Saturday, April 23, 2022
5 Secrets of Billionaires' Mind
After researching and studying the lifestyle of billionaires and tycoons through books and interview videos, let me share a brief summary of how their minds work.
1. Live Poor
Billionaires are ultra rich but prefer to live poor. They tend to be frugal and live below their means. Their wealth gives them choices to buy whatever they need and want, but they would prefer to only buy what they need.
While there are some billionaires who like to flaunt their wealth and extravagant lifestyle on social media, most billionaires prefer to keep their personal life under wraps and live simply and peacefully.
Mark Zuckerburg, founder of Meta or former Facebook wears the same t-shirts and jeans everyday and drives a simple car, Volkswagen Golf instead of luxury fast cars. Bill Gate, founder of Microsoft and once the world's richest man only wears a cheapo $10 watch just like a Singapore's minister who only wears a Casio watch.
2. Don't need a budget
With immense discipline and instilled self-control, most millionaires do not need a budget to limit their spendings. Billionaires do not need a budget not because their bank balances have abundance of cash to spend, but because they have multiple income streams, yet only need a small portion of their fortunes to live life.
Even as the incomes of billionaires grow over the years, most tend to not increase their expenditure in tandem with more income. This is in contrast to poor men mindset which tend to spend more as they earn more, trapping themselves in a poverty cycle.
Budgeting is important to track one's expenditure and avoid unnecessary spending. It is great in the early phase of financial planning for most people on the streets but for billionaires whose lifestyle remains the same despite compounding growth of income, it is not necessary for them anymore.
3. Eat and dress simple
Billionaires do not like to waste time thinking about what to eat for meals. They eat whatever they like or in the easiest manner.
The world's richest man, Elon Musk only has a breakfast bar and coffee for breakfast, which sometimes he even skipped. His lunch consists of chicken or steak for protein, grains and mixed salad. His dinner has some animal protein and veggies. When he was in college, he challenged himself to spending $1 for a day of food by only eating hot dogs, peppers and oranges.
The most legendary investor, Warren Buffet enjoys junk food and has coke and Mcdonald burgers everyday for his meals and managed to live beyond 90 years old till now. Fastfood is relatively cheap in terms of affordability to a multi-billionaire. Mark Zuckerberg also enjoys Mcdonald and was seen eating burgers with his wife many times in Mcdonald.
4. Own income producing assets
All millionaires and billionaire tycoons own income producing assets. Most own real estates and/or business empires that churn out money even when they sleep.
Billionaires know how to manage risks of their investments and periodically rebalance their portfolios to achieve the optimal allocation of stocks, bonds, real estate or intangible assets of their overall wealth.
Billionaires also have access to illiquid physical assets such as arts, commodities, antiques or private company interests or equity that are uncorrelated with the market. As long as those assets have potential growth or income producing prospects, they would be more than willing to part their money to invest in them.
5. Do not follow the crowd
Many billionaires do not have herd mentality. Some may even have contrarian mindset when it comes to personal decisions and investments. They sense opportunities during crisis and sense danger during peaceful and greedy times. Millionaires like to separate themselves from the herd, and if possible, create own new herd and get others to join it i.e.. Elon Musk?
Many billionaires live in their own world. They do not compare their wealth with others. This is a bad habit which only people on the streets do. Billionaires run their own race and compete in their businesses by delivering better goods or services to humans.
Billionaires do not listen to noises but based their decisions on sound fundamentals and logic instead of irrational behavior such as fear or greed.
Thanks for reading. Stay safe and remain strong always!
Saturday, April 16, 2022
Net Worth Update Apr 2022 | Surpassed SGD 1.25m!
The first $100k is the hardest to accumulate.
I can attest to it.
I took more than 27 years to accumulate my first $100k of wealth.
However I merely took the past 4 months to accumulate $100k of wealth!?
My net worth hits another all-time high of $1.26m.
It was $1.16m in Dec 2021 just 4 months ago.
I think the significant increase was because CPF interests, performance bonuses, dividends from SGX income portfolio and rebound of the stock markets are aligned in the the 1st Quarter of the year to bump up the paper value of my net worth.
I have completed the Retirement Sum Top-Up of $8k to my CPF Special Account and $15.3k contribution to my Supplementary Retirement Sum Account this year.
I have attained CPF Full Retirement Sum with Special Account surpassing $192k early this month. How I achieved this feat by mid 30s was also shared.
I intend to top up the Retirement Account of my mum with $8k over the next 2 months for tax relief.
In the US stock market, I plan to slowly increase my investments in growth businesses such as Alphabet Inc., Microsoft, Citigroup and perhaps even initiate a position in Amazon Inc., hoping to get on the boat before its looming stock split in Jun 2022.
On the local SGX front, I am on the lookout for the likes of high quality Frasers and Mapletree Reits to hit my target shopping prices before I add.
As my priorities are on the US and SG stock markets, I do not have plan to catch the undervalued Chinese or HK stocks. However, if I do have spare cash, I would not mind nibbling some Alibaba, Tencent or Meituan for accumulation.
The coming months in this year 2022 remain challenging and taxing financially, mentally and physically. Immense inflation and higher interest rates have caused prices of food and necessities to surge. The stock markets are likely to test lower supports, stay volatile and may enter the bear territories. WFH has begun to cease with more number of days to be spent commuting to office for work.
Stay focused. Remain on track. Be clear in our mind and heart. We will get to our goals and dreams eventually.
Tuesday, April 12, 2022
Accumulated Alphabet Inc. (NASDAQ:GOOGL)
Monday, April 11, 2022
Boosted. Another step towards normalcy
As always, stay safe and remain strong.
Wednesday, April 06, 2022
A Grossly Undervalued Property Play with 2.7% Yield Stagnating in my Portfolio
A property developer, hotel operator, student accommodation provider or medical centre owner?
Far East Orchard (O10.SI) has the attributes of all.
As always, stay safe and remain strong.
Tuesday, April 05, 2022
The 14:36 min Run that Earns $200
Individual Physical Proficiency Test (IPPT) is a key aspect of National Service in Singapore to assess the fitness level of full-time and operationally ready NSmen.
As Singaporean sons, IPPT is either an annual national service liability to attempt and pass it or rather an opportunity to reap some monetary rewards from acing it.
For the past decade, I have been seeing this as an annual affair to earn back some money from taxes for my war chest to cover some brokerage costs for buying stocks. This is despite me being an unfit guy who rarely exercise or go for runs.
I have failed my IPPT marginally last year with 49 points. See: Took my IPPT today
Today I attempt my IPPT again in this window, before going for booster jab soon and refrain from exercising for 1 month before birthday, after which the new IPPT window will start.
I did 30 push ups and 35 sit ups, clocking 38 points for static stations in my uncle age group 6.
I need 16 points from 2.4km run to pass with 51 points or 23 points to pass with 61 points for $200 reward.
I risked my weak uncle heart to run 14:36 mins.
This is kind of slow considering I was able to run below 11 mins when I was teen 20 years ago.
Nevertheless, $200 in da bank via Paynow instantly!
I passed my IPPT with 61 points!
For the past 2 months, I exercised 3 times a week doing static exercises at home to build up my stamina but did not went out for running at all.
I am happy with the result despite ending up with cramps, aches all over body but it's worth it.
Thanks for reading.
As always, stay safe and remain strong.
Sunday, April 03, 2022
How I Achieved CPF FRS in mid 30s
Let me share some strategies on how I achieved this feat.
1. Work, work and work
Not born with a silver spoon, I started working odd jobs since teenage schooling days i.e. waiter, customer service officer, ah beng handphone shop, telemarketer, factory labourer and so on. Whatever freelance jobs available, I would have done it.
I was lucky to get several job offers before graduation from university and accepted an IT job with starting pay of $3.2k, rejecting other offers in semiconductor and aerospace engineering that pay slightly lower at $3k and $3.1k respectively more than a decade ago. My income has now more than doubled.
Working in a regular job gives us income and thereby consistent CPF contributions to all 3 accounts.
I aim to always grind long enough in a job to be eligible for annual salary increments and bonuses, which all translate into higher contributions to CPF accounts.
2. Transfer funds from OA to SA
By working consistently to have regular income with CPF contributions, we can then consider whether to transfer the funds from OA to SA. This act is to boost the interest income because SA has 4% interest rate which is higher than OA's 2.5%.
In my first few years of working, I did transferred around $40k to 50k of OA funds to SA because I did not forsee buying a property using CPF OA funds anytime soon. After every monthly CPF contribution, I transferred every single cent of OA to SA, leaving OA balance zero.
This greatly helped to let my SA account have a strong foundation to compound and start growing earlier at a higher rate.
3. Retirement Sum Top-Up
As my income grew, I accumulated more disposable cash. So after a few years of working, I started to make cash tops ups to my CPF SA through the Retirement Sum Top-Up (RSTU) scheme for tax relief.
4. Earn at least $6k asap
From working consistently in a regular job with decent salary increments, it is possible to propel our active income to hit the maximum amount which is subjected to CPF contributions. This magic figure is $6k.
Try to work smart, upskill and learn, add value, gain valuable experience, sucking up to bosses if need be, to get the promotions for higher pay, or job hop to other companies or roles with higher pay or salary ceiling and strive to earn a salary of at least $6k as soon as possible in your career.
If you do not like to be a slave working for others, let your creative brain juices and entrepreneurial spirit motivate yourself to build up a business empire which provide decent goods, services or solutions that alleviate human pain points, to churn growing revenues and profits. Easier said than done, a successful business depends on a myriad of factors, many of which are out of your control. Being self-employed or owning a great business do help greatly in boosting one's income where the sky is the limit.
I personally did not work smart nor suck up to bosses nor job hop for higher pay. I merely farmed all the increments consistently and waited for my turn to be promoted for more increments. Nonetheless, I was lucky to be in a resilient IT industry providing essential services and hence hit $6k salary when I was 31. This allows me to farm the maximum CPF contributions for both employee myself and employer portion.
In the past 5 years, I was getting maximum contributions of $37,740 annually to my 3 CPF accounts.
From having maximum CPF contributions, we could accelerate the growth of our CPF SA towards FRS earlier.
5. Voluntary contributions to CPF
We could actually make voluntary contributions (VC) to our CPF (all 3 accounts) up to the CPF annual limit of $37,740. This is common for self employed but is also possible for those who did not manage to hit the $6k salary soon enough for maximum CPF contributions.
Though VC does not earn tax relief, it will still help to gradually boost CPF savings artificially and grow the SA account faster than if we were to purely rely on CPF contributions from salary alone.
I did not take this action but would like to share about this last resort to grow our CPF SA account and make steps closer towards FRS.
Actually, I could have achieved FRS much earlier 5 years ago. However, I held back by stopped transferring any OA fund to SA because I wanted to enjoy tax reliefs from RSTU as my income grew and considered using OA fund for property purchase.
See related posts:
1. Why I do not want my CPF SA to attain FRS in 2022?
2. Why I do not want my CPF SA to attain FRS in 2020?
Thanks for reading.
As always, stay safe and remain strong.
Saturday, April 02, 2022
CPF Full Retirement Sum Attained!
After the CPF contribution for my Mar 2022 income was credited, below are my CPF account balances.
My CPF SA has surpassed $192k!!!
$192k is the CPF full retirement sum in 2021.
Hence, officially I have achieved this important milestone of FRS.
My CPF SA will be able to compound automatically at 4% to beat future FRS figures, assuming FRS increase at below 4% rate perpetually.
This will guarantee that I will be able to withdraw excess CPF savings above FRS from my CPF when I turn age 55 in 2 decades time.
Although I am happy to have conquered this feat, I am disappointed that I will no longer be able to participate in Retirement Sum Top-Up into my CPF SA from next year onwards.
This will result in lesser tax relief and hence paying more taxes to IRAS.
After all, paying too much taxes is a rich man woe, which is still financially better than not earning enough income for spending nor being eligible to pay tax.
I hope to share about how I managed to hit CPF FRS in mid 30s in a future blog post soon. Do stay tuned.
Thanks for reading.
As always, stay safe and remain strong.