Tuesday, February 15, 2022

Net Worth Update Feb 2022 | Roar Past SGD 1.2 million

S$1.222m

Today is Day 15 of the New Tiger Year.

My net worth hits S$1.222m, an all time high!

The increase of $33k from Jan 2022 is mainly contributed by this month's salary, special bonuses, CPF contributions and slight recovery in the stock markets.

My CPF has surpassed $470k. CPF SA has crossed $190k and on the brink of attaining Full Retirement Sum. 

I completed the top up of $8k to my CPF SA under Retirement Scheme Top-Up (RSTU) at the end of Jan 2022.

I started to top up my SRS account with $1k last week and plan to complete the maximum contribution of $15.3k by Apr 2022.

Moving forward, I plan to be more aggressive in my investments - seizing opportunities to accumulate more growth stocks in the US stock market while adding to existing Reits in the SGX income portfolio.

I aim to accumulate up to SGD 300k worth in stocks and Reits, and achieve a passive income of SGD 18k.

My target net worth by the end of 2022 is SGD 1.3 million.

We should always be prepared for inflation and rising prices of good and services. Investment of our own monies in growth or income producing businesses, investing of own time to learn, self develop own technical and soft skills to get better paying jobs or innovate to create our own businesses are ways to beat inflation and strive towards financial freedom instead of relying on the government for payouts or subsidies in the coming Budget.

Thanks for reading. Stay safe and remain strong always!

With love & peace,
Qiongster

Monday, February 14, 2022

Added USD100 worth of Tesla Inc.


The US stock market is still in the midst of shock and uncertainty over a looming of war with Russia invading Ukraine.

I have shared about having opened a Syfe Trade account recently and used it to nibble fractional shares of Alphabet Inc. and Tesla Inc. already.

As there are 5 free trades every month, I decided to gift myself a fractional bit of Tesla Inc. using the 2nd free trade of the month.

Just US$100 worth will do.

It is really cool to be able to buy fractional shares on Syfe Trade and even though the trade execution is not exactly real-time. The lack of commission fees for free trade more than make up for it.

I will continue to use this platform to nibble bits of great tech company shares.

Thanks for reading. Stay safe and be strong as always.

With love & peace, 
Qiongster

Tuesday, February 08, 2022

Accumulated Alphabet Inc. (NASDAQ:GOOGL)


I accumulated another share of Alphabet Inc. (NASDAQ:GOOGL) this morning.

Yesterday night I placed an order at US$2780 and went to sleep. It was filled this morning at 4.52am.


I have earlier shared on the 8 reasons Why I Invested in Alphabet Inc.

Monopoly dominance, exponential growth, ever-growing share price, strong moat, stock split, resilience, below intrinsic value make this Mega Tech stock a no brainer to own for the long-term.

In the short-term, the share price of Alphabet Inc. will be volatile and subjected to weakness due to noises of lawsuits, interest rate hikes and its counterpart Meta getting bashed to pulp for having missing targets, losing active users and possibility of quitting Europe markets. 

In the long-term post split, I believe its share price will grow by at least 20% annually, surpassing US$300 per share in 5 years and US$1000 per share in 10 years. I would be happy to continue accumulating more shares of Alphabet Inc. till Jul 2022 post split and throughout the rest of this year.


Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster

Free CRO from Mystery Box In Crypto.com


I have started my crypto journey for 3 months now.

Everyday, I would collect diamonds in Crypto.com app through daily missions such as logging in, buying USD$20 worth of crypto or watching tutorial to learn about NFTs.


By accumulating 25 diamonds, we could open a mystery box which gives a chance of winning CRO (Crypto.com) native coins, which can be used to stake for a debit card or stake ons Supercharging events to earn high returns of other crypto.

Today I opened my mystery box and here is what I got.


1.2 CRO worth 80 cents as at time of writing. Not significant but it is possible that CRO could be worth many times more few years down the road.

The government has already banned advertising of crypto by the various exchanges because crypto is a volatile digital asset not backed by any fundamentals and investing or trading in such digital asset could result in huge monetary losses. Nonetheless, as much as people queue up for S$12m or S$18m Toto lottery draw betting on money they could afford to wager, I believe crypto could form 1 to 5% of out net worth as a form of a speculative digital asset class.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster

Friday, February 04, 2022

What is the Greatest Ang Bao in Life?


First and foremost, we need to have great health in order to eat, sleep and live well. Then we can work, add value to society or create businesses to gain income and wealth.

Good health is intangible, invaluable and indispensable. We need a healthy body in order to let our mind be conditioned optinally to reap the largest dividends or Ang Baos in the form of active income regardless of whether we are salaried employees or self-employed.

With active income, then we could build up capital or war chest to invest in assets that produce passive income.

However, do always remember that we come to this earth with nothing and will leave this earth with nothing. Material wealth is not everything. 

As we are indulging in the delicacies and immersing in the joyous occasion of this festival, do remember to take care of our health as always, especially in this endemic where viruses of all variants are rampantly thriving all over this island and the globe.

Treasuring and safeguarding our own health will be the greatest Ang Bao in the new Tiger year.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster

Thursday, February 03, 2022

8 Reasons Why I Invested in Alphabet Inc. (NASDAQ:GOOGL)


I procrastinated for weeks, months and years.

Yesterday night I finally pulled the trigger to initiate a position in Alphabet Inc. (NASDAQ: GOOGL) at US$2980.


The push factor was after Alphabet Inc. announced its blowout record breaking financial results for year 2021 and a 20-for-1 stock split.

10 years ago was the best time to invest in Google. The second best time is now.

Let me share 10 reasons why Alphabet Inc. is worth investing for the long haul.

1. Everyday

We use services owned by Alphabet Inc. everyday without knowing - Chrome browser, YouTube, Gmail, Android phone, Google map and Google drive. Even this blog is owned by, and all the ads surfaced comes from Google. This company intrudes into our lives so prevalently that we may not have realised. We have been consuming the services provided by Alphabet Inc. and it has become a digital drug addiction which is impossible to quit. I believe it would be ideal to own the company which "owns" us.

2. Exponential Growth

Alphabet Inc. breaks US$200 billion in annual revenue for the first time, showing no ill effects from the ongoing global pandemic or lingering issues with the global supply chain.

Its revenue and net income have been growing exponentially over the past decade.

To own a great business with predictable growth in earnings and one that operates 24 by 7 and spins money while we sleep give us an ultimate peace of mind.

Alphabet Inc.'s Revenue


Alphabet Inc.'s Net Income

3. Stock Price only goes up in long-term

In tandem with its exponential growth in revenue and net income, Alphabet Inc.'s share price has performed well in the long term and should continue to do so.

Its share price topped US$1000 prior to previous stock split in 2014 when it was halved to around US$500 and then slowly gained more than 5 times to today's price over the next 8 years.

After the impending stock split in 15 Jul 2022, I forsee that its share price will slowly and steadily climb up from $130 to $150 range back to above $1000 in the next 5 years.

4. Strong moat

Alphabet Inc. has a dominant and strong moat in its digital advertising world, complemented by an ecosystem of search engine and Android mobile operating system which is prevalent in 73% of mobile phone globally. Google provides impeccable services at almost no cost or free to the masses in the world, and monopolizes a more than 90% market share in the Internet search industry, controlling majority of the digital world and establishing a deep and wide moat. It thereby earns massive income from the advertisement streams to fund research into delivery drones, green energy, artificial intelligence projects such as DeepMind, self-driving vehicle such as Waymo and development of IoT technology such as its Pixel mobile phone and Nest smart home devices.

5. Stock Split

The impending stock split will make its stock price attractive, affordable and assessable to retail investors once again. At a range of around US$150 per share, investors no longer have to save up to US$2k to US$3k in order to invest in one share of Alphabet Inc. Investors could perform dollar cost average to accumulate Alphabet Inc. shares over the long term. As 100 shares of Alphabet Inc. shares currently cost more than US$200k, options trading for this company is almost out of reach to most traders on the streets because one option contract involves 100 shares of the underlying company stock. 

With this stock split, trading of options of Alphabet Inc. will become a possibility for investors to generate more income. For example, shareholders could sell out-of-the-money call options to collect premiums while the stock is trending sideways and potential investors on the sidelines could sell out-of-the-money put options to commit buying Alphabet Inc. shares at a lower price than market price. 

6. Resilience

Alphabet Inc.'s digital advertisement and dominant online search business is unaffected by the global pandemic as seen from the tremendous increase in its revenue and net income over the past 2 years. Instead of being impacted by the virus, the shift of trend toward hybrid working environment and emphasis on digital world has allowed Alphabet Inc. to thrive on stronger demand for online advertising based on search results and Youtube videos.

7. Fair Valuation

Alphabet Inc. is trading at around 24 times of Price/Earning ratio which seems rather high. However, if we look at its Price to Earning growth ratio, it is only around 0.75, suggesting that it is fairly or even undervalued.

A quick check on Simply Wall Street reveals that it could be more than 40% below its intrinsic value.

8. More with Less

There are 3 classes of Alphabet Inc. stock. Class A (GOOGL) stock comes with voting rights. Class B are held by its founders and insiders and not publicly traded. Class C (GOOG) stock does not come with voting rights and are created from the 2014 stock split. GOOGL used to trade at a premium compared to GOOG because it comes with voting rights. However, over the years, GOOG has become slightly more pricier than GOOGL despite having no voting rights. This was possibly due to frequent share buybacks of GOOG shares by the company itself, resulting in lower supply and higher demand. I prefer GOOGL because it offers more at a lower price.

Conclusion

There are definitely huge risks involved when it comes to investing. Alphabet Inc., being in a monopolistic mega tech business dealing with copyrights and trademarks, is always subjected to regulatory risks and brushes with the intellectual property laws and the authorities. Its cloud computing business also fare poorer relative to Amazon.com Inc. and Microsoft. Nonetheless, it presents a great piece of business to hold patiently for the long-term future, considering the reward to risk ratio. I believe its share price will remain volatile in the short-term in the run up to stock split and will consider adding more shares should its share price tank due to irrationality because in the next decade, this company will continue to own our lives and certainly grow astoundingly.

Thanks for reading. Stay safe and be strong as always. Happy Tiger Year! HUAT ah!

With love & peace, 
Qiongster

Wednesday, February 02, 2022

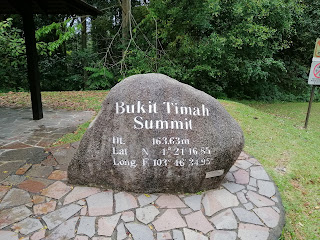
Conquered Peak of Singapore


Nothing to do on Day 2 of CNY and I went to hike Bukit Timah hill with Ms Doraemon.

Drizzling rain did not deter us from reaching the peak after 45 mins of hiking.

The weak and heavy frame of mine make things difficult on the route up to the peak as I panted heavily throughout.

Step by step. Slow and steady. I lugged myself up and conquered the peak. This is testament of the same strategy I adopted in my investment journey and pursuit of financial freedom.

Enjoyed the cool oxygen and embraced the nature after the rain stopped.


Thanks for reading. Stay safe and be strong as always. Happy Tiger Year! 

With love & peace, 
Qiongster


US$100 can nibble both Tesla and Google stocks on Singapore's Neobroker


I opened a Syfe Trade account last week.

My purpose was to leverage on such neobroker to perform dollar cost average on high quantum mega tech stocks such as Alphabet Inc. (GOOGL), Amazon.com Inc. and perhaps Tesla Inc. 

Furthermore, I could reap the free sign up, $1k top-up and first trade bonuses amounting to $60.

I then spent past 2 days toying with this neobroker account.

Nibbled tiny fractions of Alphabet Inc. and Tesla Inc for less than US$100.

The amount of US$22 used to nibble Tesla was from the S$30 sign-up bonus, meaning I gotten 0.025 share of Tesla free from Syfe!


Things may not always go according to plan in life. 

This morning, Alphabet Inc. announces a set of amazing results together with a 20-1 stock split to make its stock price affordable.

This means that each share price of GOOGL and GOOG will theoretically be around US$150 after split in Jul 2022.

Hence, I do not need such neobroker for Alphabet Inc. anymore. However for Amazon.com Inc. and Berkshire Hathaway Inc., I will still need it to nibble fractional shares as I could not afford to invest US$3k or US$470k every month.

Thanks for reading. Stay safe and be strong as always. Happy Tiger Year! 

With love & peace, 
Qiongster

Tuesday, February 01, 2022

Where are our CPF monies?


Are our CPF monies our monies?

Where are our CPF monies?

We only see numbers on the CPF website or app. No debit card or means to withdraw before age 55.

Even upon reaching age 55, many could not withdraw much CPF monies due to not meeting the minimum sum requirement.

These are the common dilemna people face.

Let me try to address and convince ourselves on these doubts in this post.

Official source from Factually explains that CPF monies are invested by the CPF Board in Special Singapore Government Securities (SSGS). SSGS are issued specially by the Government to CPFB.

In my opinion, I interpret that CPFB "lent" or "passed" our CPF monies to the Government. An "IOU" (an informal 'I Owe You' document acknowledging debt) was signed in the form of a special bond called SSGS.

In a way, CPFB is the trustee of our CPF monies, which are used to buy special "IOU" bonds that pay us our 2.5% and 4% interests in our CPF OA and SA, MA or RA savings accounts respectively.

Our next question is: What and how does the Government deal with the CPF monies?

The proceeds from SSGS are pooled with the rest of Government funds, such as Government surplus, and proceeds from land sales.

The co-mingled funds are invested by the Government's fund manager, GIC, for long-term returns.

GIC was incorporated in 1981 to invest the government's assets for long-term returns.

CPF monies are not managed by Temasek.

I interpret that our CPF monies are indirectly pooled together with the Government monies to become the war chest that GIC use to invest for the long-term to generate returns.

Many people are unhappy about our CPF monies becoming the "Government's monies", missing out the "IOU" bond part which pays attractive bonds interests in return.

Not everyone is comfortable with own own CPF monies being lent to others to invest without our consent.

However, we have to understand that if CPFB merely keeps our CPF monies and do nothing, will be be able to earn 2.5% or 4% interests? Our monies will be eroded by inflation over time. $1 becoming 50 cents by the time we retire.

In a nutshell, our CPF monies are trusted to CPFB and indirectly managed by GIC.

Let us move a step further to investigate how and what does GIC invests in, using "our CPF monies" and/or "the Government's monies".

According to the FAQ page on GIC website, GIC is a fairly conservative investor, with a globally diversified portfolio spread across various asset classes. Most of the investments are in the public markets, with a smaller component in alternative investments such as private equity and real estate.

From the GIC Annual Report 2021, this table shows the asset mix of GIC's investment portfolio.


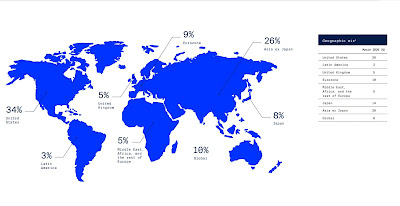
The geographical distribution of the GIC portfolio as at 31 Mar 2021 is shown below. Investments in US and Asia excluding Japan make up 60%.

These high level info are not enough to satisfy our curiosity.

I am interested to find out specifically which US stocks do GIC invest or wager on.

A quick check on whalewisdom.com revealed the top holdings of GIC Pte Ltd based on US Security and Exchange Commission filings.


I am surprised with these unfamiliar (at least to me) names of US listed companies invested by GIC. 

More than US$5 billion vested in an American online food ordering and delivery platform, Doorbash Inc. (DASH), more than US$2 billion vested in a midstream energy company, Tallgrass Energy (TGE1), more than US$1.5b vested in a leading global drug development, laboratory and lifecycle management company, PPD, Inc. (PPD), $1.3b vested in a leading China carrier and cloud neutral Internet data center service provider, VNet Group (VNET) and $1.1b vested a diversified environmental services company in GFL Environmental Inc. (GFL).

I am not able to get more details of which Chinese businesses do GIC invest in. But from the Evergrande turmoil, we learnt that GIC has been investing in Chinese Real Estate for the past 2 decades. They are also vested in China bonds.

Hope these have satisfied our curiosities on where our CPF monies went to.

Thanks for reading. GXGX! Happy CNY! HENG ONG HUAT AH! 

With Love & Peace,
Qiongster


Disclaimer: This post is written entirely based on my personal opinion and factual findings from credible sources in the Internet and does not constitute any form of recommendation, news nor investment advice.




Monday, January 31, 2022

Portfolio Update Jan 2022

It is time to review my investment portfolios as the first month of 2022 comes to an end.

The stock markets are still undergoing a correction phase under continuous immense noises engulfing Fed tapering, interest rates hikes, inflation fears, Omicron variant fears, rise of US Treasury yields, looming market crash and so on.

My stance and plan are clear. To remain invested, slowly and steadily increasing investments in income-producing assets or growth businesses regardless of all conditions and noises.

My SGX Income Portfolio value plunges to $264k from $272k last month. As this is a Reit heavy portfolio, the looming of 4 to 5 interest rate hikes lead to a corresponding large impact on the share price of most Reits even though the impact to most Reits that have hedged their loans is relatively small. I am not too concerned about short-term volatility even though this may result in a drop in my net worth, because I am more focused on long-term passive income. As long as fundamentals do not change, I will not panic sell any of my holdings, but rather add them slowly instead.

My US Growth Portfolio value increases to US$7.3k from US$6.9k. I injected around US$1k into Moomoo trading account as it encountered margin call due to holding Palantir put options while its share price keeps plummeting. I am on the lookout to initiate new or add positions in tech stocks soon.

My SRS Ultra Long-Term Portfolio value decreases to $100.6k from $102k. The decrease is mainly due to tanking of Keppel DC Reit which is offset by the spike in OCBC, both attributed to interest rate hike.

Portfolio Actions

1. Added 1,500 shares of Mapletree Industrial Trust at $2.63.

2. Redeemed 1 share of Meituan (HKG.3690) 20% discount at HK$168 on Tiger Broker.

3. Redeemed 1 share of Tencent (HKG.0700) 10% discount at HK$417.24 on Tiger Broker.

3. Redeemed 1 share of Walt Disney 20% discount at price of US$123.91 on Tiger Broker.

4. Rolled down 2 units of Palantir by closing PLTR220121 put option with $22 strike price at US$6.6 and sold PLTR220819 put option with $20 strike price at US$6.1.

5. Bought 1 share of Citigroup at US$66.20 with US$10 stock voucher.

6. Bought 1 share of Dell Technologies at US$56.88.

Portfolio Dividends

1. Received $112.50 from Savings Bonds on 3 Jan.

2. Received $116.88 of dividends from Mapletree Logistics Trust on 12 Jan.

3. Received $873 of dividends from Capitaland Integrated Commercial Trust on 28 Jan.


SGX Income Portfolio

US/HK Growth Portfolio

Moomoo


Tiger Broker


Total Portfolio Value : US$7.3K


SRS Ultra Long-Term Portfolio


Thanks for reading. It is CNY eve today. Wishing everyone Heng Ong Huat in the coming Tiger Year!

With Love & Peace,
Qiongster


Sunday, January 30, 2022

Mapletree Logistics Trust 3Q FY21/22 Results


Mapletree Logistics Trust (SGX.M44U) announced its 3Q FY21/22 Results on 28 Jan 2021.

Most importantly, dividend per unit (DPU) increases by 5.8% Year-on-Year to 2.185 cents from 2.065 cents in 3Q FY20/21.

Gross revenue and net property income increases 19.3% and 17.4% respectively as compared to 3Q FY20/21.

As advanced distribution of 1.461 cents has been paid on 12 Jan due to private placement, a balance DPU of only 0.724 cents will be paid on 22 Mar.

As of 31 Dec 2021, MLT has a portfolio of 167 properties valued at S$11.5 billion. Portfolio occupancy was decent at 97.8% with WALE of 3.6 years. Portfolio average rental reversion was positive at 2.5%.

On capital management, gearing ratio was healthy at 34.7% with an average debt duration of 3.5 years. However, with the completion of the proposed acquisition of 16 properties in China and Vietnam, its gearing ratio is set to increase to 39.1%. Hence, it is not surprising if another equity fund raising is on the cards sooner than later for the next acquisition.

The logistics sector had remained resilient throughout the pandemic as demand continues to benefit from structural trends such as e-commerce and supply chain diversification.

In terms of outlook, the global economy is expected to recover but curbed by advent of Omicron virus variant and increase in interest rates in some advanced economies.

At share price of $1.69, based on estimated annual dividend of 8.6 cents, MLT yields around 5% which is beginning to look attractive. However, I do believe that its share price will remain weak in the short-term though long-term wise, its fundamentals have not changed and is posited to soar to greater heights while providing long-term investors with a steady and consistent stream of perpetual income.

Thanks for reading. As always, stay safe and remain strong.

With Love & Peace,
Qiongster


Saturday, January 29, 2022

First CPF Financial Assignment of 2022

It has become a routine for me to top up my CPF Special Account under the Retirement Sum Top-Up Scheme (RSTU) at the beginning of the year.

As CPF interests are computed on a monthly basis, we could reap higher returns by topping up our CPF account(s) in Jan rather than Dec. For an amount of $8k based on 4% interest rate, the difference between Jan and Dec could be more than $290.

Under RSTU, the main benefits are to earn the risk free 4% interests from CPF SA and to enjoy tax reliefs for up to $8k.

I have topped up $8k today, reaping $320 of interests and saving $560 of taxes (at 7% rate), thereby gaining $980 or 11% worth of benefits! 


Moving ahead, I plan to top up my Supplementary Retirement Scheme (SRS) account.

Meanwhile, I am like a predator hunting for preys as many high quality Reits and stocks are been hammered. I smell opportunity again.

The results reporting season is ongoing for some of the Reits. I will just sit back and enjoy the numerous Ang Baos trickling in after the Chinese New Year when the Reits in my portfolio start to pay dividends.

Thanks for reading. As always, stay safe and remain strong.

With Love & Peace,
Qiongster

Friday, January 28, 2022

Capitaland Integrated Commercial Trust 2H 2021 Results


Capitaland Integrated Commercial Trust (CICT) [SGX.C38U] announced its 2H 2021 results today.

Dividend per unit (DPU) for 2H 2021 declines by 8.9% to 5.22 cents as compared to 5.73 cents in 2H 2020.

As advanced payment of 4.85 cents for the period 1 Jul 2021 to 15 Dec 2021 has been paid on 28 Jan (coincidentally today) due to private placement, only DPU of 0.37 cents will be paid on 15 Mar 2022.

Even though gross revenue, net property income and distributable income for 2H 2021 increases significantly compared to 2H 2020, DPU declines due to the dilutive private placement causing a larger number of outstanding shares (127.6m).

After the merger with Capitaland Commercial Trust on 21 Oct 2020, CICT has wholly owned Raffles City Singapore, contributing to the increased distribution income.

Portfolio occupancy was at 93.9%, with retail properties at 96.8% and office properties at 91% and integrated developments at 96%. Capita Spring achieved TOP in Nov 2021 and has only partially begun to contribute to the distribution income. Likewise, for recently acquired Australian properties such as 101 Miller Street and Greenwood Plaza in Sydney, 66 Goulburn Street and 100 Arthur Street, local properties undergoing AEI such as Six Battery Road and 21 Collyer Quay, they are expected to contribute strongly to distribution income this year.

Retention rate of tenants was 82.3% and it is disappointing to see negative rental reversion of - 7.3% for Year 1 rents vs outgoing final rents and - 3.2% for incoming average rents vs outgoing average rents. For downtown malls, the negative rental reversion is - 13.8% compared to for suburban malls' - 2.4%. This is a harsh reflection of the reality caused by WFH impact from the pandemic though.

However, it is encouraging to see tenant sales psf recovered to 87.8% of 2019 pre-pandemic times and shopper traffic recovered to 61.2% of 2019 pre-pandemic times.

CICT's aggregate leverage was 37.2% and average cost of debt was stable at 2.3% per annum. Interest coverage ratio was at 4.1 times.

At share price of $1.94 as of time of writing, an annual dividend of 10.4 cents would give CICT a yield of 5.36% per annum, which is fairly attractive. However, with the immense noises, fears and uncertainties, it is possible that CICT will see further weakness in its share price. 
I still believe that it is a no-brainer to not own this pioneer and largest Reit listed on SGX that owns the best shopping malls and top grade office buildings in Singapore. In the past 2 decades, we have seen this Reit beaten down and thrashed to pulp and then rise, awaken and reborn as always. This time will be no different.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster


Ascott Residence Trust 2H 2021 Results


Ascott Residence Trust (SGX.HMN) announces its 2H 2021 results today.

Dividend per security (DPS) increases 14% Year-on-Year to 2.27 cents as compared to 2H 2020 and increases 43% Year-on-Year to 4.32 cents as compared to 2020.

As advanced distribution of 0.545 cents has been made on 9 Nov 2021 for the period 1 Jul 2021 to 19 Sep 2021 due to private placement, a DPS of 1.726 cents for the period 20 Sep 2021 to 31 Dec 2021 will be paid to existing Security holders on 1 Mar 2022.

Distribution per Security for 2021 increases 43% to 4.32 cents and revenue per available unit (REVPAU) increases 17% to $69 from 2020, indicating a recovery in hospitality industry. REVPAU for 4Q 2021 hits $87, registering the strongest quarter-on-quarter increase at 24%. The long-stay properties continued to provide income stability, while the easing of travel restrictions and increased global activities led to a hike in demand from both corporate and leisure guests. Key markets in US, UK and Australia registered the strongest growth.

High revenue (+29.7%) for 2H 2021 compared to 2H 2020 was due to increased revenue from existing portfolio and additional contributions from the acquisition of 6 student accommodation assets in the US and 3 rental housing properties in Japan.

The distribution income for 2021 includes a one-off divestment gain of $45m, termination fee income received upon terminating the sale of Citidines Xinghai Suzhou and Citidines Zhuankou Wuhan, realised exchange gains on the receipt of the divestment proceeds, realised exchange gains from the repayment of foreign currency bank loans with the divestment proceeds.

Gearing ratio is at 37.1% with interest coverage ratio of 3.7 times. Borrowing cost is low at 1.6% per annum. It currently has $340m and $700m of untapped credit facility. 74% of the debts are hedged on  fixed rate, and this ratio is expected to rise to 80% after refinancing of another loan. Hence, interest rates hike have curbed impact on Ascott Residence Trust.

At share price of $1.02 as of time of writing and with dividend per share of $0.0432, Ascott Residence Trust yields more than 4% as it is on track towards recovery of tourism and hospitality sector. NAV per share is $1.19, signifying slight undervalue. 

I believe Ascott Residence Trust is a great long-term recovery play. While waiting with patience for the recovery of the world's tourism industry from the pandemic and reopening of countries' borders in the transition towards an endemic world, shareholders can still be rewarded with at least 4% yield.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster


Thursday, January 27, 2022

Aims Apac Reit 3Q FY2022 Results


Aims Apac Reit (SGX.O5RU) announces its 3Q FY2022 results today.

Most importantly for unitholders, dividend per unit (DPU) increases 14.6% Year-on-Year to 2.35cents compared to 2.05 cents in 3Q FY2021.

The DPU of 2.35 cents will be paid on 25 Mar 2022.

Gross Revenue and Net Property Income rises by more than 14% compared to 3Q FY2021. This is mainly due to the acquisition of Woolworths Headquarters in New South Wales, Australia and higher gross revenue from 20 Gul Way, 27 Penjuru Lane and 541 Yishun Industrial Park A (rental contribution from new master tenant commenced on Jan 2021).

Portfolio committed occupancy remains high at 97.6%, well above JTC industrial average of 90. 1%, and decent WALE at 4.85 years.

10 new and 8 renewal leases were successfully executed in 3Q FY2022 at slight positive rental reversion of 0.2%.

Gearing ratio is 37.3% with undrawn credit facility and war chest of $237.2m. Blended funding cost is slightly high at 2.8% per annum. Adjusted interest coverage ratio is decent at 3.3 times.

Moving forward, the broad economic recovery of Singapore and Australia will provide demand and support for the industrial sector, particularly manufacturing and business park space.

I believe that Aims Apac Reit is a great underrated small industrial Reit to hold for the long-term and it should continue to deliver more than 6% of dividend yield while panning for its value to be unlocked and the economy to recover.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster


Wednesday, January 26, 2022

Suntec Reit 2H 2021 Results


Suntec Reit (SGX. T82U) announced its 2H 2021 results today.

Gross revenue increases 15.3% Year-on-Year and net property income increases 30.3% Year-on-Year compared to 2H 2020.

DPU for 2021 increases 17.1% Year-on-Year to 8.666 cents.

Most importantly, DPU of 2.28 cents for 4Q 2021 will be paid on 28 Feb 2022.


It is important to note that the lower occupancy in Singapore office properties of One Raffles Quay and MBFC are partially offset by higher rental reversion of +3.2%. Overall occupancy in Singapore properties remain high at 97.5%.

There are new contributions from Nova properties and the Minster Building.

Suntec City strata office units and 9 Penang Road have been divested.

In terms of Suntec City's financial health, gearing ratio is quite high at 43.7%. All in financing cost is 2.35% per annum. Adjusted interest coverage ratio is relatively low at 2.6 times. NAV of $2.11 signifies Suntec Reit is undervalued based on share price of $1.54.

The prolonged impact of ongoing pandemic will make the recovery of convention centres and retail space owned by Suntec Reit slower than expected. Suntec Reit's tenants have a large composition of SMEs and small companies and hence may lead to early lease terminations and higher vacancies. Nonetheless, I believe Suntec Reit is a great value commercial Reit play worth getting paid more than 5% yield p.a to wait for its recovery.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster


Tuesday, January 25, 2022

Mapletree Industrial Trust 3Q FY21/22 Results


Mapletree Industrial Trust (SGX.ME8U) announced its 3Q FY21/22 results today.

Most importantly for unitholders, dividend per unit (DPU) increases 6.4% to 3.49 cents relative to 3Q FY20/21.

The DPU of 3.49 cents will be paid on 15 Mar 2022. Distribution Reinvestment Plan (DRP) has been resumed and unitholders can opt to receive their dividends in units instead. DRP is a great scheme to leverage on the power of compounding without incurring transaction or brokerage costs if unitholders do not mind the odd units. The reason for DRP is to strengthen balance sheet and to finance the redevelopment of Kolam Ayer 2.

Higher gross revenue (+31.3%) translating into higher net property income (+24.1%) do certainly look impressive. The increases were mainly driven by contributions from the acquisitions of 29 data centres in the United States and 8011 Villa Park Drive, Virginia.

Portfolio occupancy has dropped marginally from 93.7% in previous quarter to 93.6%. This was due to the low 87.4% occupancy rate of the 29 data centres in US.

The weighted average cost of debt of Mapletree Industrial Trust is 2.3% per annum and interest coverage ratio is high at 6.4 times. Gearing is a little high at 39.9%.  9.2% of total borrowings are due for refinancing in FY21/22 and 13% due in FY22/23 so the higher interest rates should have some impact on its financing costs but hopefully will not impact its DPU much this year.

I believe Mapletree Industrial Trust is a great Reit to own and accumulate for the long-term due to its track record, historical DPU growth rate and ownership of a resilient class of income producing industrial properties and data centres with long WALE. 

I currently own 8,000 shares of Mapletree Industrial Trust and intend to continue accumulating it for the long-term for stable and growing dividend income.

See related posts:

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster


Keppel Reit 2H 2021 Results


Keppel Reit (SGX. K71U) announced its second half 2021 results today.

Most importantly for unitholders, dividend per unit (DPU) drops 1.7% to 2.88 cents relative to 2H 2020, but increases 1.6% Year-on-Year to 5.82 cents.

The DPU of 2.88 cents will be paid on 1 Mar 2022.

Despite higher net property income (+15.2%) and higher distributable income from operations (+4.6%), DPU still drops due to relatively high management fees and larger number of outstanding units from private placement in Feb 2021. Keppel Reit is indeed a big boys friendly Reit rather than being retail friendly.

Portfolio occupancy has dropped from 97.9% in Dec 2020 to 95.4% in Dec 2021, signifying the slight impact caused by WFH and hybrid working culture.

It is important to note that the acquisition of Blue and William, a Grade A office building under development in North Sydney, in Dec 2021 has not fully contributed to the distributable income of Keppel Reit. However, other more recent accretive acquisitions such as Keppel Bay Tower, Pinnacle Office Park in Sydney and Victoria Police Centre in Melbourne have already contributed to the distributable income.

The average cost of debt of Keppel Reit remains decent at 1.98% per annum and interest coverage ratio is fair at 3.9 times. Gearing remained decent at 38.4%. Only 5% of total borrowings are due for refinancing in FY 2022 so the higher interest rates should have only limited impact on its financing costs and hopefully will not impact its DPU much this year.

I believe Keppel Reit is only a decent pure office Reit for existing unitholders to hold but not attractive enough to entice new investors to initiate new position and accumulate because there are better Reits that offer greater reward to risk ratio.

I do like the high quality office properties owned by Keppel Reit though. The main reason I invested in Keppel Reit 6 years ago was to own a stake of Marina Bay Financial Centre and other Grade A office buildings for close to 6% dividend yield.

I currently own 10,351 shares of Keppel Reit in my SRS account at net average cost of $0.71 and will continue holding it for the long-term despite its lacklustre potential and growth under the highly paid mediocre management.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster

Monday, January 24, 2022

Keppel DC Reit 2H 2021 Results


Keppel DC Reit (SGX. AJBU) announced its second half 2021 results today.

Most importantly for unitholders, dividend per unit (DPU) increases 7.4% Year-on-Year to 9.851 cents.

As an advanced distribution of 1.421 cents has been paid on 20 Oct 2021, the DPU is 3.506 cents to be paid on 10 Mar 2022.

Even though DPU increases due to higher distributable income, this set of results is not perfect because net property income (NPI) and gross revenue actually decreases 4.3% and 4.0% respectively as compared to 2H 2020.

It is important to note that acquisitions completed in Dec 2021 - Guangdong Data Centre, London Data Centre In Bracknell and the M1 network infrastructure have not fully contributed to the distributable income of Keppel DC Reit.

I believe Keppel DC Reit should be able to continue grow its DPU, but at a slower rate.

Higher risks, lower growth rate, higher interest rates potentially increasing financing costs and losing its pure data centre play status to Digital Core Reit have caused the share price of Keppel DC Reit to weaken in recent months to a fairly attractive level of $2.20s.

The average cost of debt of Keppel DC Reit remains low at 1.6% per annum and interest coverage ratio is high at 10.8 times. Gearing remained healthy at 34.6%. The higher interest rates should have some but limited impact on its financing costs and hopefully impact its potential DPU growth.

I believe Keppel DC Reit is still a great investment to hold and accumulate because it owns data centre assets that provide the infrastructure upon which our mobile applications, social media, data engineering, artificial intelligence and cloud computing thrive to drive the digital world.

Thanks for reading. Stay safe and be strong as always. 

With love & peace, 
Qiongster