Thursday, November 30, 2023

Portfolio Update November 2023

This is a quick update of my investment portfolios on the last day of Nov 2023.

My SGX Income Portfolio value rebounds to $316k from $301k.

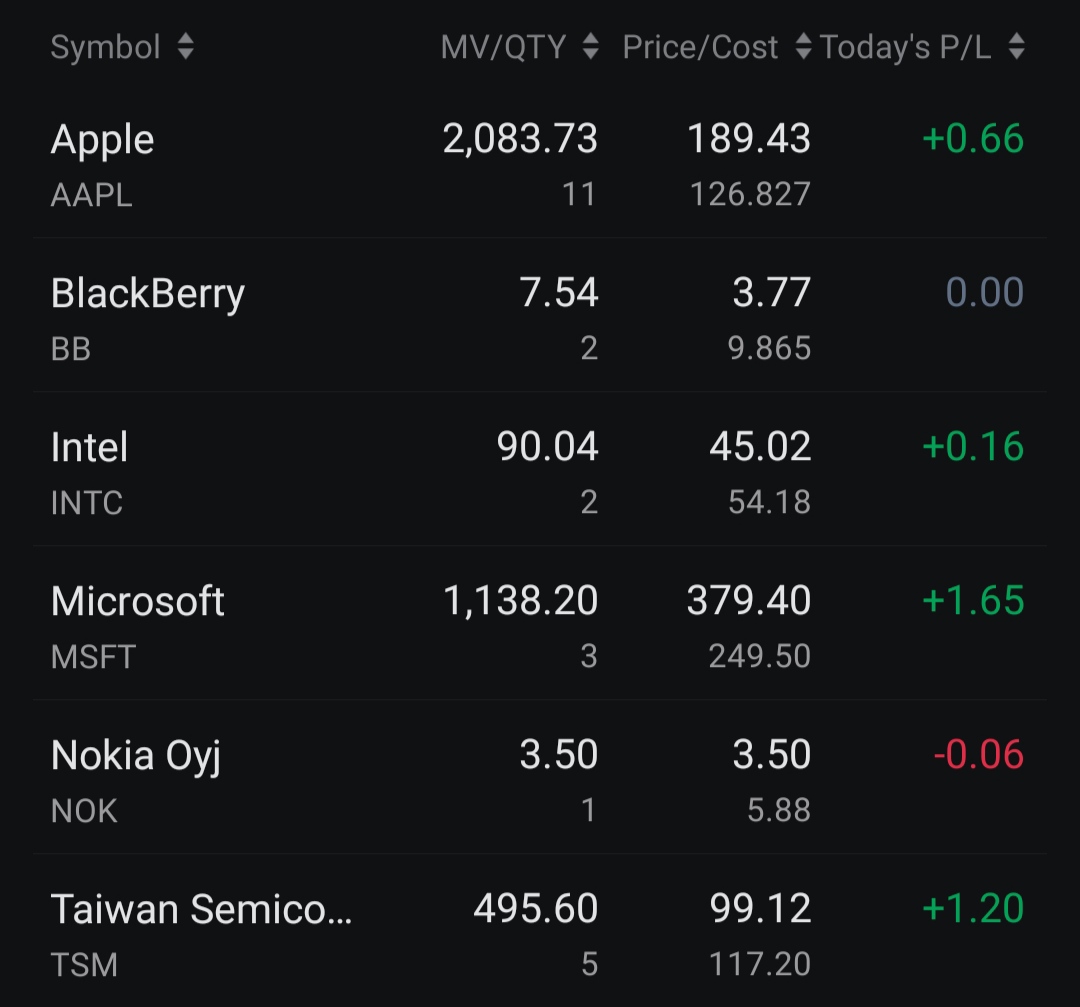
My US/HK Growth Portfolio value rises to US$17 from US$16k.

My SRS Ultra Long-Term Portfolio value inches up to $137.4k from $136.4k.

The US stock markets have hit new heights amidst increasing certainty of pivoting interest rates, ongoing wars and lingering fears of global recession. US 10-year and 30-year government yields have retraced from record highs and the Federal Reserve is expected to maintain interest rates steady at the 5.25 to 5.5% range till 2024. Local S-Reits have rebounded and stabilised slightly helping my SGX Income Portfolio recover back some paper losses. 

Scary storylines about economies, monetary policies and geopolitical tensions just keep repeating, causing chaos and fear amongst investors and traders While being clouded by uncertainties, immense noises and fears, it is crucial that long-term investors like us stay calm, unwavered and focused in our investment objectives. Make the best out of current situation by allocating our financial resources into high yield risk-free bonds, stable and high quality income-producing assets, or strong growth businesses tactfully.

I will continue stashing away idle cash in high yield cash funds and risk-free Singapore Savings Bonds while also adding high quality S-Reits or local bank stocks to my SGX income portfolio if opportunities arise in the next few months. I have no plan to add US/HK stocks.

Portfolio Actions

Nil

Portfolio Dividends

1. Received $428.35 of dividends from Savings Bonds on 1 Nov.

2. Received $270.00 of dividends from Guocoland on 16 Nov.

3. Received $192.00 of dividends from DBS on 27 Nov.

4. Received $187.15 of dividends from Astrea 7 A-1 PE Bond on 27 Nov.

5. Received $481.60 of dividends from Frasers Centrepoint Trust on 29 Nov.

6. Received $89.65 of dividends from Suntec Reit on 29 Nov.


SGX Income Portfolio

Portfolio Value = $316k


US/HK Growth Portfolio

Moomoo


US$3.8k


Tiger Broker


US$12.4k


Syfe Trade

US$0.9k


Portfolio Value = US$17k

SRS Ultra Long-Term Portfolio

Portfolio Value = S$137.4k


Thanks for reading. Stay focused and remain steadfast as always!

With love and peace, 
Qiongster

Wednesday, November 29, 2023

Memento Mori: RIP Charlie Munger


Investment guru, trusted side-kick of Warren Buffet, Charlie Munger passed away today at the age of 99.

His estimated net worth of $2.6 billion has been left behind, rendering "Die with Zero" an insurmountable task for billionaires.

Charlie Munger was the vice-chairman of Berkshire Hathaway and believed in buying great businesses at fair or undervalued prices, leveraging on the magical power of compounding over long-term to grow his wealth tremendously.

A simple man, with no frills lifestyle, embracing frugality and down-to-earth spending habits, he modestly lived in the same house for decades and ate only simple meals and fast foods.

He is a great role model for those of us striving towards achieving financial independence or freedom.


It is important to know that no matter how much wealth or success one attain in life, only taxes and death are certain.

All of us cannot escape the harsh reality of returning back to earth as ashes.

Memento Mori

Remember you must die.

Thank you for reading.

With love & peace,
Qiongster

Monday, November 27, 2023

Applied for Singapore Savings Bonds (SBDEC23 GX23120)


The Dec 2023 tranche of Singapore Savings Bonds (SSB) has an average yield of 3.4% over 10 years.

The first 6 years yield a flat 3.3% per annum; 7th year yields 3.36% p.a, 8th year yields 3.58% p.a. and 9th, 10th years yield 3.68% p.a.

Even though such yield is lower than other low to risk-free alternatives such as T Bills and money market funds which easily yield more than 3.5% currently, it is higher than many fixed deposit rates on offer by local banks as well as CPF OA rate of 2.5% p.a.

If we also consider the great flexibility, liquidity of SSB for redemption and long-term lock down at above 3% p.a for the next decade, then this tranche of SSB is fairly enticing for us to park our spare cash at zero risk, capital guaranteed for the mid to long-term. 

We could redeem SSB anytime, earning interest at 3.3% in the short-term while getting back our capital for deployment to other investments or large item purchases unlike T Bills and bank fixed deposits which would incur losses or forfeit of interest with premature withdrawals. Do note that the redemption process of SSB can be up to 1 month of lead time.

I decided to apply for $10k of this Dec 2023 tranche using my savings and war chest.

There it goes.


S$1b is up for grabs.

The first payment will be on 1 Jun 2024 and this bond will mature on 1 Dec 2033.

If you are interested in this tranche of SSB, do note that the application dateline is on today, 27 Nov 2023, 9pm for online applications.

Both short-term and long-term treasury bond yields have decreased recently and these could signal that the yields of SSB will be lower in next few months. I will still be happy to inject more cash into SSB in the next few months if the yields stay above 3%. My ultimate aim is to max out the personal limit of S$200k soon.

At the same time, I also redeemed an old tranche of SSB (SBMAY18 GX18050E) with an average yield of 2.39% and currently only yielding 2.54% in its 6th year. It is hence a no brainer decision to recycle the funds into next month's SSB.


Thank you for reading.

With love & peace,
Qiongster
Saturday, November 11, 2023

Net Worth Update Nov 2023

My net worth stagnates at S$1.5m for Nov 2023.

I have been saving frugally, reducing expenses and conserving capital for purchase of Singapore Savings Bonds since I return from Seoul holiday trip.

CPF is the bulk 37% of my net worth. I have already achieved full retirement sum in CPF SA and topped up my Medisave account to the basic healthcare sum of $68.5k early this year.

Cash and war chest constitute 18% of my wealth. In the current high rate environment, my cash is being stashed away in bank fixed deposits yielding more than 3% p.a., in Fullerton cash funds under custody of Moomoo and Tiger Broker, and in Money Market Funds held by Phillips Capital yielding around 3.5% p.a. with interest paid daily.

Together with 9% of my risk-free Singapore Savings Bonds ($130k) and relatively low-risk Astrea 7A PE bond ($9k), CPF, cash and war chest amount to 64% of my net worth as safe assets. I intend to subscribe to the coming Dec 23 tranche of SSB with average yield of 3.4%.

Stocks and Reits constitute 22% of my net worth. Together with SRS account which forms 8% and are deployed mainly into local stocks and Reits, they are the 30% of riskier assets in my financial portfolio.

Slow but steady, I remain on track towards the path of financial freedom. Ignore the noises. Be greedy when others are fearful. Be fearful when others are greedy. Be contented when others are hungry.

Thank you for reading. Stay focused and remain steadfast as always!

With love & peace,
Qiongster

Tuesday, October 31, 2023

Portfolio Update October 2023

This is a quick update of my investment portfolios on the last day of Oct 2023.

My SGX Income Portfolio value plunges to $301k from $320.8k.

My US/HK Growth Portfolio value inches up to US$16 from US$15k.

My SRS Ultra Long-Term Portfolio value decreases to $136.4k from $142.2k.

The US stock markets have corrected recently amidst increasing certainty of prolonged high interest rates, ongoing wars and lingering fears of global recession. US 10-year and 30-year government yields hit record highs and the Federal Reserve is expected to maintain interest rates steady at the 5.25 to 5.5% range till 2024. As a result, local S-Reits were hammered and impacted my SGX Income Portfolio greatly. Such storylines just keep repeating, causing chaos and fear amongst investors and traders.

Clouded by uncertainties, immense noises and fears, it is crucial that long-term investors like us stay calm, unwavered and focused in our investment objectives. Make the best out of current situation by allocating our financial resources into high yield bonds, stable and high quality income-producing assets, or growth businesses tactfully.

I intend to continue growing my cash in cash funds and risk-free Singapore Savings Bonds while also monitoring and adding high quality S-Reits or local bank stocks to my SGX income portfolio in the next few months.

Portfolio Actions

1. Rollup 1 unit of Alphabet, GOOGL231117 call option with $105 strike price by buying back at US$17 and selling 1 unit of GOOGL240621 call option with $115 strike price at US$18.90.

Portfolio Dividends

1. Received $148.86 of dividends from Savings Bonds on 2 Oct.

2. Received $56.08 of dividends from Capitaland Ascott Reit on 11 Oct.


SGX Income Portfolio

Portfolio Value = $301k


US/HK Growth Portfolio

Moomoo

US$3.3k


Tiger Broker

US$11.9k


Syfe Trade

US$0.8k


Portfolio Value = US$16k

SRS Ultra Long-Term Portfolio

Portfolio Value = S$136.4k


Thanks for reading. Stay focused and remain steadfast as always!

With love and peace, 
Qiongster

Thursday, October 26, 2023

Applied for Singapore Savings Bonds (SBNOV23 GX23110V)


The Nov 2023 tranche of Singapore Savings Bonds (SSB) has an average yield of 3.32% over 10 years.

The first 6 years yield a flat 3.21% per annum; 7th year yields 3.3% p.a, 8th year yields 3.52% p.a. and 9th, 10th years yield 3.63% p.a.

This is not very appealing considering that other low to risk-free alternatives such as T Bills and money market funds easily yield more than 3.5% currently. However, this yield is higher than many fixed deposit rates on offer by local banks.

However if we consider the great flexibility, liquidity of SSB for redemption and long-term lock down at above 3% p.a and above CPF OA yield of 2.5% p.a. for the next decade, then this tranche of SSB is fairly decent for us to park our spare cash at zero risk, capital guaranteed for the long-term. 

We could redeem SSB anytime, earning interest at 3.21% in the short-term while getting back our capital for deployment to other investments or large item purchases unlike T Bills and bank fixed deposits which would incur losses or forfeit of interest with premature withdrawals. Do note that the redemption process of SSB can be up to 1 month of lead time.

I decided to apply for $10k of this Nov 2023 tranche using my idle war chest funds.

There it goes.


S$1b is up for grabs.

The first payment will be on 1 May 2024 and this bond will mature on 1 Nov 2033.

If you are interested in this tranche of SSB, do note that the application dateline is on today, 26 Oct 2023, 9pm for online applications.

Both short-term and long-term treasury bond yields have increased recently and these could signal that the yields of SSB will be higher in next few months. I am happy to inject more cash into SSB in the next few months if the yields stay above 3%. My ultimate aim is to max out the personal limit of S$200k soon.

Thank you for reading.

With love & peace,
Qiongster

Saturday, October 14, 2023

Net Worth Update Oct 2023

My net worth dips to S$1.499m for Oct 2023.

This is after savings from salary, CPF contributions and dividends collected.

CPF constitutes the bulk 37% of my net worth. I have already achieved full retirement sum in CPF SA and topped up my Medisave account to the basic healthcare sum of $68.5k early this year.

Cash and war chest constitute 18% of my wealth. In the current high rate environment, my cash is being stashed away in bank fixed deposits yielding more than 3% p.a., in Fullerton cash funds under custody of Moomoo and Tiger Broker, and in Money Market Funds held by Phillips Capital yielding around 3.5% p.a. with interest paid daily.

Together with 9% of my risk-free Singapore Savings Bonds ($110k) and relatively low-risk Astrea 7A PE bond ($9k), CPF, cash and war chest amount to 64% of my net worth as safe assets. I intend to subscribe to the coming Nov 23 tranche of SSB with average yield of 3.32%.

Stocks and Reits constitute 22% of my net worth. Together with SRS account which forms 8% and are deployed mainly into local stocks and Reits, they are the 30% of riskier assets in my financial portfolio.

Life is exciting in a post pandemic world. Ignore the noises. Remain on track. Be greedy when others are fearful. Be fearful when others are greedy. Be contented when others are hungry. 

Thank you for reading. Stay focused and remain steadfast as always!

With love & peace,
Qiongster

Saturday, September 30, 2023

Portfolio Update September 2023

This is a quick update of my investment portfolios to conclude the end of Sep 2023.

My SGX Income Portfolio value drops to $320.8k from $327k.

My US/HK Growth Portfolio value falls to US$15 from US$15.4k.

My SRS Ultra Long-Term Portfolio value inches up to $142.2k from $140.2k.

The US stock markets have corrected recently amidst increasing certainty of prolonged high interest rates and lingering fears of global recession. As a result, local S-Reits also tanked. Such storylines just keep repeating, causing chaos and fear amongst investors and traders.

Despite being immersed by uncertainties, immense noises and fears, it is crucial that long-term investors like us stay calm, unwavered and make the best out of current situation by investing and deploying our financial resources into stable, high quality income-producing assets or growth businesses tactfully.

I plan to continue adding high quality S-Reits or local bank stocks to my SGX income portfolio in the next few months while also growing my cash in cash funds and risk-free Singapore Savings Bonds.

Portfolio Actions

1. Bought 2,000 shares of Parkway Life Reit at $3.60 in SRS.

Portfolio Dividends

1. Received $270.65 of dividends from Savings Bonds on 4 Sep.

2. Received $138.00 of dividends from Savings Bonds in SRS on 4 Sep.

3. Received $136.74 of dividends from Mapletree Ind Trust on 5 Sep.

4. Received $300.18 of dividends from Keppel Reit in SRS on 8 Sep.

5. Received $404.08 of dividends from Keppel DC Reit in SRS on 14 Sep.

6. Received $327.00 of dividends from MPACT on 14 Sep.

7. Received $954.00 of dividends from CICT on 15 Sep.

8. Received $407.40 of dividends as 244 shares under DRP from Mapletree Log Trust on 19 Sep.

9. Received $178,50 of dividends from Aims Apac Reit on 22 Sep.

10. Received $205.10 of dividends from Capitaland China Trust on 25 Sep.

11. Received $42 of dividends from OUE Limited on 28 Sep.


SGX Income Portfolio

Portfolio Value = $320.8k


US/HK Growth Portfolio

Moomoo

US$3.3k


Tiger Broker

US$10.8k


Syfe Trade

US$0.9k


Portfolio Value = US$15k

SRS Ultra Long-Term Portfolio

Portfolio Value = S$142.2k


Thanks for reading. Stay focused and remain steadfast as always!

With love and peace, 
Qiongster

Friday, September 29, 2023

Passive Income in 3Q 2023 and 9 months of 2023


Almost 3 quarters of 2023 have whizzed by with a blink of an eye.

Let me provide a quick update on my passive income for 3Q 2023 and first 9 months of 2023.

From 1 Jul to 30 Sep 2023, I collected the following dividends.

$122.50 SSB (3 Jul)
$145.87 SSB (3 Jul) SRS
$372.62 Mapletree Ind (6 Jul)
$576.00 Aims Apac Reit (20 Jul)
$90.00 SSB (1 Aug)
$524.45 UOB (18 Aug)
$192.00 DBS (24 Aug)
$1,800.00 OCBC (25 Aug) SRS
$222.24 Ascott Reit (29 Aug)
$86.95 Suntec Reit (29 Aug)
$90.00 Wilmar (30 Aug) SRS
$157.80 Ascendas Reit (31 Aug)
$145.00 Comfortdelgro (31 Aug)
$298.45 IREIT Global (31 Aug)
$188.00 ST Eng (31 Aug) SRS
$270.65 SSB (4 Sep)
$138.00 SSB (4 Sep) SRS
$136.74 Mapletree Ind Trust (5 Sep)
$300.18 Keppel Reit (8 Sep) SRS
$404.08 Keppel DC Reit (14 Sep) SRS
$327.00 MPACT (14 Sep)
$954.00 CICT (15 Sep)
$407.40 Mapletree Log Trust (19 Sep) DRP 244 Shares
$178.50 Aims Apac Reit (22 Sep)
$205.10 Capitaland China Trust (25 Sep)
$42.00 OUE Limited (28 Sep)

The total amount of passive income in Q3 2023 is $8,375.53, an 18% YoY increase from Q3 2022's $7,086.93.

Together with the $13,466.19 passive income in the first half of 2023, my passive income in the first 9 months of 2023 is

$21,841.72


On track of achieving my target of $22k passive income for 2023.

Time in the market beats timing the market. In the long-term, I am happy to remain primarily invested locally in SGX for passive income, while having a little exposure to US tech stocks for some growth.

My ultimate goal is to own an investment portfolio valued at one million dollars yielding at least $50k of passive income annually. Currently, I am at about half of the journey as my SGX income portfolio and SRS ultra long-term portfolios are valued at around $500K and dividends are projected to be around $25k or more for this year.

My motto is to live frugally, save up, invest in any bear or bull market conditions, slowly and steadily build up my investments in stocks, Reits and risk-free government bonds.

I look forward to collecting more dividends as passive income in the final quarter of Year 2023.

Thanks for reading. Stay focused and remain steadfast as always! Huat ah!

With love and peace, 
Qiongster

Thursday, September 28, 2023

Initiated Position in Most Defensive S-Reit


"The best time to plant a tree was 20 years ago. The second best time is now."

Parkway Life Reit has been on my radar for a very long time since I missed its IPO in 2007.

I had always missed the opportunity to own it as my orders were either not filled or its share price keeps rocketing northward for the past decade and I was unwilling to pay the premium to own it.

The time has finally arrived as its share price corrected from the highs of $5.10s in end 2021 to $3.60 today.

My humble order using idle SRS funds was filled today.

This gives me the chance to initiate a position in a defensive healthcare REIT with a yield of around 4% p.a. for the long term.

Parkway Life Reit owns a unique class of resilient healthcare properties - 57 freehold nursing homes in Japan, specialist clinics in Malaysia and 3 hospitals in Singapore including the likes of Mount Elizabeth and Gleaneagles.

This Reit has never performed any equity fund raising for acquisitions but rely on internal funding and bank loans to expand its assets since IPO to achieve its ever growing dividends.

It is very defensive because of its long-term leases with the hospitals and nursing homes, with stable income supported by positive annual escalation. The properties are located predominantly in Japan and Singapore with ageing population demanding ever-increasing healthcare services.

Furthermore, it is prudent in managing foreign income from Japanese Yen by putting in place Japanese Yen foreign exchange contracts till 1Q 2027 and hedging 77% of interest rate exposure.

I like this Reit and am happy to initiate a small position in my ultra long-term SRS portfolio.

Thank you for reading.

With love & peace,
Qiongster

Monday, September 25, 2023

Reflections on my 6D5N Seoul Trip


Hangang River

I just came back from a maiden 6D5N budget Seoul trip.

It has been an eye-opener and awesome experience.

As shared in earlier blog post, this was a last minute impromptu trip booked merely 3 weeks in advance with minimal planning.

Here is an overview of the itinerary.

Day 1: Dongdaemun (hotel neighbourhood) - Dongmyo flea market, Dongdaemun Gate, Dongdaemun Design Plaza, Cheonggyecheon.

Dongmyo flea market where locals rummage through piles of old branded clothes i.e. Ralph Lauren, Tommy Hilfiger for 1k to 3k Korean won each only.

Dongdaemun Design Plaza, an artsy & musical hub akin to Singapore's Esplanade


Dongdaemun City Gate

Cheonggyecheon

Day 2: N Seoul Tower, Namsangol Hanok Village, Myeongdong

N Seoul Tower

Entrance of a traditional house in Namsangol Hanol Village

Shopping paradise in Myeongdong for skincare products, branded clothes and street food

Day 3: Gangnam, Coex Mall Starfield Library, Underground Goto Mall, Banpo Hangang Park

Gangnam Statue outside Coex Mall

Underground Goto Mall at Express Bus Terminal subway station where local ladies shop for stylish Korean clothes at affordable prices

Banpo Hangang Park overlooking Banpo bridge

Day 4: Insadong, Tapgol Park, Annyeong Insadong Mall, Ssamzigil Mall

Insadong street with many teahouses, eateries and artsy shops

Tapgol Park featuring Korean national heroes and a Pagoda

Ssamzigil mall is a complex selling art and crafts items and some providing caricature services

Annyeong Insadong Mall, another cultural shopping complex with galleries and artsy stuffs

Day 5: Olympic Park, Yeouido Hangang Park

Olympic Park

Lone tree hill within Olympic Park where many Kpop music videos and dramas are filmed

Lake in Olympic Park

Yeouido Hangang Park overlooking Mapo bridge and Seoul cityline

Hordes of picnickers, mainly youngsters chillaxing by the Hangang river while enjoying the cold breeze and food

Day 6: Travel to Incheon Airport for noon flight

Journey on AREX train to Incheon Airport

Arrival at the busy Incheon airport for flight home

Due to shortage of time, there are many places of interest that we did not manage to cover - Hongdae, palaces, Buchon Hanok Village, National Museum, Seoul City Wall Trail, Lotte World, other parks and so on.

Let me briefly share on some takeaways from this trip.

1. Cash is still King

Although most shops and restaurants in Seoul accept credit cards or multi-currency debit cards in general, most did not reject cash even for shops with automated ordering kiosks. There is always a way for manual order to accept cash. Top up of Tmoney card at the kiosks in subway stations is via cash only. In Seoul, I believe the more Korean Won we bring will only allow us to get all the items we like and food we crave for. Cash is still King!

2. Transport is robust but complex

The subway system in Seoul is much more complicated and complex than Singapore's. There are 23 lines, each with different colours- navy blue, light blue, purple and so on. Usually, from point A to point B, there are more than 3 routes and we need to find the most efficient route by using apps such as Kakao map or Seoul subway map. Fewer stops do not mean shortest path.


One downside to the efficient subway system is the fleet of stairs one need to climb or long distance to walk to reach a particular subway exit or make train transfers. Some of the subway stations were built decades ago and were not equipped with lifts. 

3. Language is not a barrier with the help of technology

Google translator app or other translator apps can take in text, voice inputs, images and translate Korea words into English on the fly. Hence language barrier can be overcame. Although not fool proof, such translator apps help us greatly to understanding food menus in Korean words and assist us to communicate with Koreans who could not understand English.

4. Great food at great prices

The food in Seoul is great and awesome at affordable prices but not cheap compared to Singapore. From ginseng chicken soup, fried chicken, fast food burgers, ramen, fried rice to gimbap, all are delicious and nice. However, there are no hawkers nor coffeeshops like in Singapore offering S$3.50 noodles or caifan. The average baseline prices for food in Seoul for e.g. a bowl of plain noodles is at least 6,000 won or S$6.20. That is why we need to budget more for food when in Seoul and be prepared to eat what we like or crave for without bothering about prices.

5. A City Rich with Culture and Vibes

There are 12 main Riverside Hangang Parks, 5 Royal Palaces and not to mention the numerous mountains, hills, smaller parks spread across the city and a few nearby islands.

The city is immersed in nature and is a shopping paradise for cosmetics, cultural items, branded and stylish clothes.

In many ways similar to Singapore, there is a good mixture of tradition with modernity, ancient but futuristic, cheap and expensive.

Thank you for reading.

With love & peace,
Qiongster