Sunday, July 19, 2020

What will I do about Sembcorp Industries? Part 2


After the announcement on the recapitalisation of Sembcorp Marine and demerger of Sembcorp Marine from Sembcorp Industries in Jun 2020, I have shared my opinion on the possible action plans for this demerger.
What will I do about Sembcorp Industries?

Sembcorp Industries has announced their poor but expected 1H 2020 results on 17 June 2020 and reported a $131m loss, compared to $191m profit in 1H 2019.

The urban segment is able to make profits of $38m. The energy, corporate and marine divisions all chalked up losses, with marine contributing up to $117m of losses.

It is important to note that the loss on paper is largely attributed to the one-off exceptional items of $191m. Writing off of asset values and impairment of investments are accounting treatments and do not result in actual cashflows.

The energy business actually has a net profit of $156m before a write off of $161m to become accounted with a net loss of $5m.


Source: Sembcorp Industries Presentation Slides for 1H 2020 Results

The energy business is still largely profitable from operations despite general drop of oil and gas prices in recent months. However, the profit from operations is dragged down by business operations in Singapore and India. In Singapore, the 47% drop in operational profit is due weaker demand caused by Covid-19 and lower price of high sulphur fuel oil (HSFO). In India, the $29m drop in operational profit is caused by lower electricity demand and lower prices by Thermal Power Project 2.


It is disappointing that there is no interim dividend declared for 1H 2020 as the company board has prudently decided to defer the dividend consideration to the full year.

Despite gauging $2 to be a fair value and having plenty of opportunities to sell it above $2, I am keeping my little shares in Sembcorp Industries after considering having to suffer a massive loss from an average holding cost of $3.30 and having kept them for more than 5 years already. I decided to give Sembcorp Industries a fighting chance for another 5 years to propel its energy utilities business if they can get rid of the disastrous marine sector.

Sembcorp Industries will be able to start off with a clean slate in Sep 2020 if the EGMs approve the recapitalisation and demerger plans by end Aug.

It is important to note that the ex-dividend price of Sembcorp Industries can drop to possibly as low as $1 and we should be conservative to not assume the share price of the "free" Sembcorp Marine shares will trade above $0.20. There is no free lunch. Institutional funds have pumped up the share price of Sembcorp Industries and unloaded to retail investors for the past month.

We should not buy Sembcorp Industries at $1.80 now thinking of getting a good deal from the "free" shares or eyeing a great trading opportunity speculating on the EGMs to approve the recapitalisation and demerger plans. We should buy Sembcorp Industries at $1.80 now only if we believe in the profitability and resiliency of its energy and urban business in the long run, and as an additional bonus, there is a possibility of a future merger of some sort between Sembcorp Marine and Keppel O&M.

I am doing nothing and will wait for the demerger to pan out. I will consider cutting loss above $2.

Thanks for reading.

Love & Peace,
Qiongster

Saturday, July 18, 2020

Net Worth in Jul 2020 Inching towards SGD 1 million


My net worth increases $5k to $945.5k from Jun 2020, inching towards SGD 1 million.

More than half of my net worth (55%) is illiquid in CPF, SRS accounts and Insurance plans. Hence, I target to build up the percentage of my liquid net worth in cash and stocks.

The component of stocks (Equity & Reits) - 21% is almost on par with my Cash -19%. A short term target is to boost them to 25%.

I am fortunate to have a job immune from Covid-19 to allow me continue farming the monthly cashflows and CPF contributions.

My primary warchest in the Phillips POEMS money money fund is depleted. Funds in SRS account are fully invested. Recent actions:
Nibbled Frasers Centrepoint Trust
Bought Mapletree NAC Trust

Secondary warchests of $230k idling in Fixed Deposits and Savings Bonds will be activated only if market crashed again to attractive levels at STI below 2200 or S&P 500 below 2000.

As a late bloomer, having no liabilities such as car loan or housing mortgage allow me to continue  living frugally, conserving ammunition in war chests while staying invested to collect dividends and sleeping soundly in peace.

The coming months and years will be challenging for many people, companies and countries. Facing huge erosions of bottom lines and great operational impact due to the health crisis, it is difficult to survive in the new normal world. Inevitably, more companies will go bust and many more people losing jobs. The economic recovery, if it has not even started, will be long, gradual and uneven.

I am optimistic on the future yet also mentally prepared for the worst that could happen.

Stay on course, play safe and have no fear.

Thanks for reading.

With Love & Peace,
Qiongster

Friday, July 17, 2020

My frugal $2 hellthy meal from Mcdonalds


Lengendary investor Warren Buffet eats McDonald's for lunch at least 3 times a week even at 88 years old.

He enjoys junk food and coke.

Once a while, Qiongster enjoys fast food too.

But Qiongster is cheapo and frugal.

Following his $2 lunch from the hawker, he is trying to repeat the feat for a hellthy $2 lunch from McDonald's.

It is possible. By buying the cheapest chicken burger at $2, adding extra lettuce. And redeem a small unsalted fries.


The freebie is earned from giving feedback in McDonald's app, which integrates delivery feature with feedback and rewards functions.

There is option of free small coke, fries or cone ice cream with any purchase. 

A McDonald's lunch for $2.

Recession proof and inflation beating. 

Thanks for reading. 

With love & peace, 
Qiongster


Thursday, July 16, 2020

Possible to buy lunch with $2 in Singapore?


Buying lunch with $2 in 2020 in Singapore?

It is actually possible. 

Many hawker centres in Singapore generally offer affordable meals. 

I got my packed rice from a mixed vegetable stall in Kim Keat hawker, Toa Payoh Lorong 7 for $2!


Rice with fried dory fish and vegetables. 

My humble and frugal meal for a cheapo me. 

For 20 cents more, there will be one more vegetables.

For 50 cents more, one more meat. 

For 80 cents more, one more veggie and one more meat. 

Too bad I only have $2 in my wallet. Other payment modes are not accepted. Only cash.

No wonder this stall has the longest queue in the hawker centre. 

Cheap, affordable value meals at its best for the workers, low income and elderly. 


Similar to hunting for undervalued stocks to invest in, I enjoy undervalued meals to beat inflation and boost my savings rate, especially during recession and uncertain times now amidst a global health pandemic.

I do not crave for overpriced dining in restaurants but I enjoy collecting dividends from the Reits that own the land upon which the restaurants reside. 

I believe Singapore is still a relatively cheap for food and essentials but expensive for large items like car and housing.

In this capitalist society, it is important to be frugal, to save up and boost emergency funds and war chests to own more income producing assets so as to always be well prepared for retirement, rainy days or retrenchment which will be a popular corporate action in the coming future, if not to achieve financial freedom ASAP. 

Thanks for reading. 

With Love & Peace, 
Qiongster


Sunday, July 12, 2020

Lessons from Singapore GE2020 for Investment

The Singapore General Election is done and dusted. The PAP government returned to power with 83 of 93 seats and an overall vote of 61.24%, a drop of 8.7% from 69.9% in 2015.

I just wanna share some takeaways and thoughts from observing the whole campaign and results.

1. What goes up will come down
Since the independence of Singapore in 1965, the PAP has held 100% of the Parliament seats until 1984, the first time it lost 2 out of 74 seats to opposition parties. Nevertheless, the PAP has held more than 90% of all the seats till the 21th century. This 2020 GE is the first time PAP has less than 90% of all the seats as it lost 10 seats to the WP.

Similar to the stock market, strong resistance will be experienced by the index and stock price at high levels. A retracement or correction to the next support level is a natural process of a moving indicator. Just like how a stock price or index is reflective of expectations of the buyers and sellers on the value and earning prospects of the underlying company business, the number seats or votes obtained by a political party is testament of its popularity and mandate given by the people.

2. Risk management
With a clear mandate given to the incumbent government, it is obvious that Singaporeans are risk adverse and prefer stability over volatility. By sticking to the proven and existing government to lead Singapore out of the crisis, it is a lower risk investment decision compared to overhauling the government into unproven hands of opposition political parties that have no experience in governance which is too high risk to bear.

However, by swinging more votes towards the opposition parties, it is a clear signal that Singaporeans are willing to hedge their portfolio by taking on more risk to order to provide more balances and checks on the PAP government.

In investment, we should also manage the risk of our portfolios, adjust our equity to cash to bond ratio according based on varying risk appetites in various circumstances.

3. Quality is more important than Quantiy
While there are 11 political parties competing in the GE, only 2 managed to get seats in the Parliament. Singaporeans are shrewd to elect only the high calibre politicians into the parliament and not Tom, Dick or Harry.

In investment, we should focus on choosing quality stock and reits with high earnings visibility to invest instead of having a large number of mediocre counters in our portfolio.

4. Character
While there have been varying character reviews and assassination attempts on some candidates during the process of election campaigning, some candidates with outstanding character traits such as exuding humility, humbleness, hardwork, compassion, intelligence, grit eventually prevail and achieve positive results deservedly.

In investment, it is important to possess the positive character traits to achieve  to achieve great results. By being  disciplined to stick to own investment plan and philosophy, hardworking in research of company financial, being humble to accept all opinions and criticisms even after attaining financial freedom or success, one will continue to learn, improve and eventually reap more fruits of own labour.

5. Minimal impact of polls on stocks as government and economy are status quo


The Singapore government remains the same. Economy is still sluggish. We should not forget that we are still in the midst of a health pandemic.

As past trends of STI shows, after a GE, there will only be minimal volatility on the stock market as the fluctuation of STI before and after GE is within 10%.

The utmost and most immediate task by the newly elected government is to lead Singapore out of the present crisis and economic slump.

In life, the only constants are death and taxes. This GE has very little bearing on our lives as everything is status quo. Thanks for reading.

With Love & Peace,
Qiongster


Friday, July 10, 2020

Top up CPF Retirement Account of parent to save tax

I just topped up $5k cash into my mum's CPF Retirement Account and will top up another $2k next month.


This is under the CPF Retirement Sum Topping Up (RSTU) scheme.
Source: From CPF Website

Under the scheme, we can top up the CPF Retirement Account of our parent with cash or using our own CPF savings.

The benefits from topping up $7k to parent's CPF Retirement Account are:
a) Tax savings of $490 for tax bracket of 7%
b) Interest of $280 per annum earned in the retirement account based on 4% p.a rate and not factoring in the following

The first $60,000 of your combined CPF balances, of which up to $20,000 comes from your OA, earn an additional 1% interest per year. Since 2016, an additional 1% interest is paid on the first $30,000 of combined CPF balances for all members aged 55 and above.

Hence, I will enjoy at least $770 of "earnings" from this move.

I have already topped up my CPF Special Account $7k in Jan and Feb 2020 to enjoy the same benefits.

I have also topped up $15.3k into my SRS account to enjoy tax relief.

CPF is a controversial double-edged retirement financial instrument. There are advocates and naysayers on CPF. The advocates know how to make use of the system to their own benefit while those naysayers are pawned by the system.

I decided to make full use of the CPF and SRS system for my benefit.

Not forgetting today is General Election day with a possibility for a change of Singapore government but will not change the CPF system overnight. Happy voting folks! Thanks for reading.

With Love & Peace,
Qiongster

Thursday, July 09, 2020

Bought Mapletree Nac Trust

After nibbling Frasers Centrepoint Trust at $2.31 last week and seeing it rebound towards $2.50 levels, I become greedier.

As I have depleted my cash war chest, I am looking to use the remaining funds in SRS for targets that are worth a quick punt and yet can be kept for long term if the punt fail.

I targeted Parkway Life Reit, Capitaland China Retail Trust, Mapletree Nac Trust and IReit. I placed orders for them at 3.37, 1.26, 0.95 and 0.72 respectively. In the end, order got filled for Mapletree Nac Trust and there I have it.


Priced at 0.95, it is at 0.67 of the book value of $1.412. Conservatively, if it is able to pay out DPU of $0.06 for FY2020/21, the yield is above 6%. Undervalued, at relatively attractively yield, backed by strong sponsor and the only Reit with properties all over North Asia, I believe this is a fairly good deal.

However, the downside risks can be attributed to worsening of political tensions in Hong Kong and dent to retail industry caused by the pandemic resulting in higher vacancy and negative rental reversion. In the long run, the retail spending power in China and Hong Kong is still a growing force not to be reckoned with.

Technically, supported by 20 day MA of 0.95 and 100 day MA of 0.93, the downside is limited relative to it possibly clearing the resistance at 1.03 and breakout to greater heights. Hence the risk reward ratio is very attractive.


Every crisis breeds opportunity. We need to seize the opportunities presented during crisis to our advantage. Thanks for reading.

With Love & Peace,
Qiongster

Thursday, July 02, 2020

Nibbled Frasers Centrepoint Trust

Frasers Centrepoint Trust (FCT) SGX: J69U announced the acquisition of an additional 12.07% stake in PGIM Real Estate AsiaRetail Fund (ARF) on 1 Jul 2020 for S$197.2 million.


ARF owns Century Square,Tiong Bahru Plaza, Hougang Mall, White Sands Mall, Tampines Mall and Central Plaza office block in Singapore and a mall in Malaysia.

PGIM Real Estate is actually the property investment division of Prudential Financial.

FCT's stakes in this Fund will increase to 36.89% after the deal is completed by the end of Jul 2020.

Its sponsor, Frasers Property will own the remaining 63.11% in ARF.

This deal is fully funded by debt and possibly at its current low borrowing rate of 2.44%.

This acquisition is slightly yield accretive and reinforces FCT's strategy of investment in suburban malls in Singapore.

However, gearing will increase from 34.7% to closer to 40%.

As highlighted by DBS Research, “We see this as the key catalyst for both FPL and FCT if the group is able to gain further control of the properties and convert its stake into actual physical asset ownership,”

It is highly possible that FCT will slowly up its stakes in the ARF and eventually add 5 more suburban malls in Singapore into its portfolio to be a dominant suburban mall Reit.

Though my war chest is depleted, I am tempted to ride on this wave of sururban malls exposure by FCT.

I regret selling off the FCT that I nibbled in May 2020 as after I sold at $2.07, the share price of FCT climbed to hit $2.60 before tapering off to $2.30 in recent days.

I learnt my mistake from timing the market and decided to nibble a small byte of it at $2.31 this time, hopefully for long term keep.

Not too long ago in Jun 2019, FCT had a preferential offering of 31 for 1000 units at $2.35. Hence, I believe below $2.35 is a fair price to accumulate FCT. 

I still believe FCT, at current valuation, is still fairly discounted to factor in the impact from Circuit breaker due to Covid-19, lower DPU and negative rental reversions in the short term.

In the long term, I am confident FCT can rebound back to the $2.80 or $3.00 levels. Its DPU will also recover to above 12 cents annually eventaully.


Thanks for reading,
Qiongster

Tuesday, June 30, 2020

Portfolio Update Jun 2020

Portfolio value increases $4k or 2% to $191k.

Most of the counters in the portfolio are trending sideways or dipped slightly due to worries about the worsening of Coronavirus situation globally as economies are opening up.


Executed portfolio rebalancing actions:
Sold Starhub at $1.39
Bought Mapletree Industrial Trust at $2.73

SRS portfolio value inches up $2.7K or 4%.


Collected all the dividends for 2Q 2020 and started to build up more than $1k in war chest.

Achieved a passive income of more than $7k from the first half of 2020.

The stock market is in a limbo state. Not fearful enough for a huge correction and yet no positive catalyst for further run up.

I believe there will be further weakness and downside to the stock markets till Nov 2020, when the US presidential election takes place and after which we shall see the real long and gradual recovery of the global economies as the virus tapers down and full effects of recession kick in.

Nonetheless, my plan is to stay invested by picking up undervalued bank counters such as UOB and accumulating more solid Mapletree Reits slowly in 2H 2020.

Thanks for reading.

Love and Peace,
Qiongster

Monday, June 29, 2020

A Reit that I do not dare to sell again

AT&T Data Center at 402 Franklin Road, Brentwood, USA
Source: Brentwoodhomepage.com

On 20 May 2013, I bought Mapletree Industrial Trust (SGX: ME8U) at $1.55 as a novice investor.

Its share price plunged to the $1.20 - $1.30 region for me to incur a loss of more than 20% for the next few months.

Back then, Reits were not a popular financial instrument. All industrial Reits were traded at discounts to NAV.

On 24 Apr 2014, I eventually sold MIT at $1.435. At a loss of 5% after dividends. Buy HIGH Sell LOW.

The share price of MIT rose steadily in the next 6 years in tandem with rising net property income, DPU with quality acquisitions along the way. The share price breached $2 in Dec 2017 and scraped $3 in Dec 2019.


Then comes the market crash in Mar 2020 when its share price dived from $3.04 to $1.87 and then made a V shape recovery back to $2.98.

After observing the defensiveness and resiliency of MIT during a crisis, I decided to nibble MIT at $2.38 during the halfway recovery in Apr 2020 before its Q4 2020 results announcement. As expected, the impact of the health crisis to its net property income is minimal and its share price continued to rise. I actually sold it off for a small profit thinking that there would be retracement.

I realised it was a grave mistake trying to time the market. I should have always kept MIT long term.

The FOMO in me prompted another purchase of MIT at much higher price $2.73 after MIT was announced to replace SPH in the Straits Times Index. I knew its share price has a high chance to recover back to pre-Covid levels and it really did.

On 23 Jun 2020, MIT announced a $350m private placement to acquire the remaining 60% interest in 14 Data Centers from Mapletree Redwood Data Center Trust. Though dilutive, this deal is DPU accretive and will increase the % of resilient data center assets in its property portfolio. This acquisition  serves to sustain the share price of MIT above $2.80, which is the private placement price for institutional investors.

Even though the share price of MIT is $2.95 at the time of writing presenting decent capital gains, I do not dare to sell it again as I learnt my mistake of timing the market and believed strongly that MIT will do well in the long run in terms of DPU and share price.

It will take extreme bad news and immense fear before institutional investors and funds sell off MIT for its share price to correct and every dip will be a good opportunity to add based on dollar cost averaging.

Riding on the waves of digitalization, Industry 4.0 and advent of data analytics, MIT is a solid and steady Reit well positioned for the future and should be a long term investment. NOT FOR TRADING NOR SHORTING.

The above is just my personal sharing and opinion and is by no means any recommendation of investment advice. Thanks for reading!

Love & Peace,
Qiongster


Sunday, June 28, 2020

Passive Income in 2Q 2020 and 1H 2020

Half the calamitous year of 2020 has passed and it is time to stocktake the dividends collected as passive income from my investments.

I collected the interests from Singapore Savings Bonds (SSB) from Apr to Jun, and dividends from the companies and Reits in my CDP and SRS portfolios.

The total amount of passive income in Q2 2020 is $4,151.49.


Together with the $3,192.33 passive income in Q1, my passive income in the first half 2020 is $7,343.82, which is actually lesser than my monthly active income, but able to cover all my basic necessities and essential expenditure for 6 months, except for my monthly insurance premiums.

I would be able to declare myself being financially free if not for the hefty whole life insurance premiums which was not a savvy decision made some years back.

The following are the streams of CDs, interests and contra trade profits.
$98 Savings Bond (1 Apr)
$165.54 Mapletree Ind Trade Profit (30 Apr) 
$97.50 Savings Bond (4 May)
$60.49 Frasers Centrepoint Trust Trade Profit (18 May)
$88 Suntec Reit (28 May)
$144.92 Keppel Reit (29 May) SRS
$100.10 Mapletree Com (29 May)
$470 ST Eng (29 May) SRS
$109.50 SSB (1 Jun)
$126.50 Netlink Trust (3 Jun)
$72 Sembcorp Ind (3 Jun)
$59.22 Mapletree Log Trade Profit (4 Jun)
$66.30 Capmall Trust (5 Jun)
$657.72 OCBC (5 Jun) SRS
$264.60 Comfortdelgro (9 Jun) SRS
$210 OUE (10 Jun)
$112.50 Starhub (12 Jun)
$447.60 Frasers L&I Trust (26 Jun)
$576 Aims Apac Reit (29 Jun)
$225 UOB (29 Jun) 

I hope to collect more passive income in 2H 2020 and wish that the economy starts to crank up again. 

The effects of recession caused by this health crisis have not been fully effected yet. We should continue to save for more rainy days and thunderstorms ahead. Build up war chest for investment opportunities. Grow our emergency funds to be ready for stocking up food supplies or unforseen spending needs as we do not know what lies ahead in the future. 

I still believe in proper portfolio allocation to stay invested in the stock markets instead of having 100% cash waiting to time another big market crash. Unless we are traders who only speculate in index or stock price movements and do own any long term positions of income producing assets, we should avoid being overly smart or accurate. 

While there are immense challenges ahead, I am still optimistic that the long term future will be great for mankind. There is no obstacle that man cannot overcome.

Thanks for reading!

Love and Peace,
Qiongster

Friday, June 26, 2020

What is Richness in Life?

What is richness in life? 

It is not always about being wealthy, but rather it could be richness in our mind, richness in health or richness in the spirit. 

The best things in life are always free and not measurable by money. They are intangible. 

The abundance of love, the plentiness of oxygen in the air, the constant flow of water. They are all essential elements for us to survive.


In this world, no one is poor because everyone is given the precious commodity of time - 24 hours or 86400 seconds a day

We ourselves determine whether we live poor or rich. One can be not wealthy but if one adopts a correct mindset, he or she can feel rich too. It all boils down to the mind. Richness can comes in the form of contentment, satisfaction, happiness, healthiness ....

So everytime if you feel poor, take a deep breath and appreciate the time you still have to enjoy in this world.

With Love & Peace,
Qiongster


Friday, June 19, 2020

My Net Worth Growth Over Past 7 Years

I started to track my net worth since May 2013.

That was after working for more than 2 years as a fresh grad and having paid off entire tuition fee loans.

Hit SGD 100K net worth in Jan 2014 at age of 27.

In 2016, I realised there is "money" in my CPF account too. So after some thinking, I decided to factor the numbers in CPF into my net worth. Until now, I am not sure if this is the right thing to do.

I feel richer when I factor my CPF. So there was a boost since Jan 2016.


My short term target is to cross the psychological SGD 1 million figure.

Achieving this milestone will give me the morale boost to believe that anything is possible in life. It is possible for an employee, a salaried worker, a poor pauper to become a millionaire in a capitalist society driven by consumer spending, wage slaves, properties and business ownerships.

A million net worth will present a strong foundation to achieve my ultimate financial freedom goal before the age of 40.

My intermediate target within next 3 years is to achieve a net worth of SGD 1.5m with $2k/mth passive income with a $400K portfolio

My ultimate target is a net worth of SGD 2m with $4k/mth dividends from an $800k portfolio. This day will come. Certainly I believe.

Thanks for reading.

Love & Peace,
Qiongster


Tuesday, June 16, 2020

Net Worth Update Jun 2020

My net worth increases $29k to $940k from $911k in May 2020.

More than $20k is gained from the portfolio due to continued recovery in the stock markets.

I also collected more than $2k of dividends in the month of June alone.

Savings from monthly salary and CPF contributions make up the rest of the increase.

After ploughing more than $40k investing in the likes of Comfortdelgro, SATS, OCBC, CapitaLand Mall Trust, Frasers Logistics & Commercial Trust, Mapletree Industrial and UOB from Mar to May, I have sat back and relaxed while watching them recover and rally, thereby contributing to the increase of my net worth. I have removed deadwood such as Starhub and the other deadwood, Sembcorp Ind suddenly had become a potential gem for the future after the de-merging plan was announced.


My emergency funds and secondary war chests in Singapore Savings Bonds and fixed deposits are intact.

Primary warchest in POEMS Money Market Fund is topped up with dividends but depleted due to portfolio rebalancing and I have no plans to invest more in the short term.

I plan to use the cashflows from next few months of income to pay off insurance premiums, income taxes and top up mum's CPF retirement account for tax relief. Hopefully by Sep, I can build up my warchest and invest more again.

Well, I am on track towards the one million milestone. With further easing of Circuit Breaker measures, and as the economy slowly recovers, I believe that my net worth and passive income will soar to greater heights! Every crisis is an opportunity indeed.

Thanks for reading!

With Love & Peace,
Qiongster

Thursday, June 11, 2020

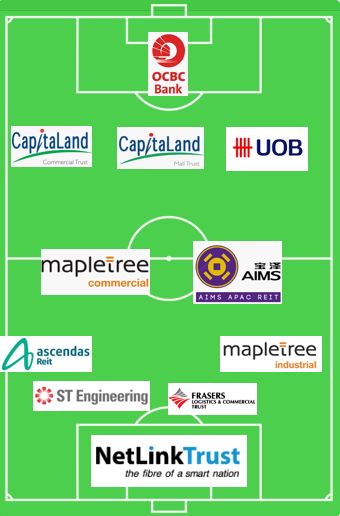
My Starting 11 players on the Investment pitch

Since the stock market crashed in Mar 2020, I have taken opportunities to add on and re-balance my investment portfolios in CDP and SRS to brace for the new decade.

As football leagues across the world are restarting the season, just as the world economies reopen, I am unveiling my strongest 11 players on the investment pitch!


The formation is 4-2-3-1.

Goalkeeper: Netlink Trust as it is a monopoly business which is more static in terms of growth and share price movement.

Central defenders:
ST Engineering deals with defence business, Smart Nation, Internet of things, robotics etc. and is a relatively resilient business. Its weakness is the Aerospace sector which is heavily impacted by the pandemic.

Frasers L&C Trust owns a well diversified portfolio of freehold industrial, logistics properties and business parks in Australia and Europe and is a relatively solid and resilient Reit in terms of business operations of the tenants.

Left Back:
Ascendas Reit is a tough tackling, big sized and high stamina left back. It owns industrial properties in Singapore and business parks in the US and can give consistently increasing dividends while continuing to grow its portfolio.

Right Back:
Mapletree Industrial Trust is a young and speedy right back. It can give consistently increasing dividends and its numerous Man-of-the-Match performances have earned it place in the Straits Times Index national team.

Midfielders:
Aims Apac Reit is a well-managed small industrial Reit that provides consistent dividends. Despite its small size, it has stamina to sustain matches without incurring injuries and will throw occasionally in tackles to defend the ball.

Mapletree Commercial Trust is more of a box to box midfielder. It links up the defence and attack. It owns top quality properties that can thrive on the Greater Southern Waterfront in Singapore. It has proven to be consistently reliable in terms of providing increasing dividends and capital gain in share price. During a crisis, it will play safe and conserve stamina by retaining dividends.

Central Playmaker:
Capitaland Mall Trust is an all-rounder attacker who likes to provide assists. Owning high quality shopping malls all over Singapore, it provides the best locations for dining, shopping and relaxation. However, it is a victim of social distancing measures and shutting down of non-essential retail stores during the pandemic. During a crisis, it will play smart and conserve energy by retaining dividends. It has a never give up attitude and will blossom to become the greatest world class playmaker when the crisis is over.

Left Winger:
Capitaland Commercial Trust is a dependable winger who is going to retire soon. It will be merged with Capitaland Mall Trust. It owns top quality Grade A commercial skyscrapers in Singapore and is under immense pressure from the growing needs and popularity to WFH due to the pandemic.

Striker:
OCBC is a versatile, agile and speedy target man. No doubt it is suffering from low interest rates, slow growth in loans, its recent surging performances has depleted most of its energy. Time for a rest!

Right Winger:
UOB is an old school winger who likes to throw in crosses and bend free kicks like Beckham. Like the striker, its recent surging performances has used up most of its energy. Time to take a long rest after vomiting $0.75 CD and bounce back stronger as we overcome the health crisis.

Reserve bench:
Goalkeeper: Sembcorp Ind (Suffered long term depression but recovering well after deciding to kick its useless son, Sembcorp Marine out of the house)
Defenders: SATS (Broken foot and undergoing physiotherapy learning to walk again)
Midfielders: Far East Orchard, OUE, Guocoland, Suntec Reit
Strikers: Ascott Reit (Awaken from coma), Comfortdelgro (Injured), Keppel Reit

Thanks for reading!

Qiongster

Monday, June 08, 2020

What will I do about Sembcorp Industries?

I own a small quantity of Sembcorp Industries (SCI) shares in my portfolio. They were purchased in 2015 when I decided to invest in a great business dealing with energy generation, renewable energy, waste management, urban development and marine industries. It was a defensive growth stock paying decent dividends of 3.5% yield then.

However the past 5 years, declining earnings and dividends plagued Sembcorp Industries as it was dragged down by the decline in marine and offshore and plummeting oil prices inflicted on its marine arm, Sembcorp Marine (SCM), of which it owns a 61% stake.

After factoring in all the dividends collected over the past 5 years, my average holding cost is $3.30, suffering a more than 50% capital loss. There were plenty of chances to sell Sembcorp Industries to make decent profits but I chose to hold on due to faith in its essential global utilities business which has immense potential in the long term.

To be honest, I am tempted to cut my losses on several occasions to make my money work smarter and harder. I would get more dividend income and return on equity by investing in Reits or other growth stocks than waiting for the recovery of Sembcorp which seems too distant and improbable.

On 4 Jun 2020, the shares of Sembcorp Industries and Marine were halted from trading. On 8 Jun 2020, the plan for recapitalisation of Sembcorp Marine and demerger of Sembcorp Marine from Sembcorp Industries was announced.


SCM will raise $2.1 billion from rights issue. Parent SCI will subscribe to all its entitled rights for up to $1.5 billion by writing off the loan it provided to SCM in 2019. The other $0.6 billion will be raised from existing SCM shareholders or Temasek if SCM shareholders decided not to exercise their rights shares at a heavily dilutive ratio of 5 rights shares for every 1 existing SCM share.


After the rights issue, shares of SCM owned by SCI will be given away to existing SCI shareholders at a ratio of between 427 and 491 shares per 100 shares of SCI owned. SCI will not own any stakes of SCM anymore. Temasek which currently owns SCM indirectly through SCI, will own SCM directly together with SCI shareholders.


The financial position of SCI greatly improve after SCM is decoupled from its entity. 


The plan will be executed only if at least 50% of both SCI and SCM shareholders are in favour during the EGM.

What existing Sembcorp Industries shareholders can do? 

1. Do nothing
Let the rights issue and demerger take place and receive the SCM shares converted from debts to equity. No further capital injection is required. There is a fairly high chance that SCI shares will still hover between $1.50 to $1.80 in the short term while SCM shares are traded in the $0.20 to $0.30 range after the rights issue. Decoupled from marine industry, SCI may start to do well in its energy and utilities business in the long term and the share price may converge closer to its post demerger NAV of around $1.90. Who knows the "free" SCM shares may be acquired by Temasek or Keppel Corp to be merged with Keppel O&M arm or rising oil prices may bring the marine and offshore back to life again?

2. Increase stakes of SCI
Purchase more SCI shares to average down their holding price or increase shareholdings to speculate on the possible increase in share price of SCI in the short term and also to leverage on the strengthening position of SCI and ride on the potential growth of renewable energy and utilities business in the years to come.

3. Sell off partial stakes
Reduce exposure to SCI by recycling partial capital back for other investment opportunities and keep a sizeable amount of SCI positioned for the long term recovery and growth.

4. Sell off everything
Get back all capital from SCI to avoid complications and invest in other businesses or contribute back to war chest for better opportunities.

What I will do?
As I only hold a small quantity of SCI and have already held it for more than 5 years, I can afford to do nothing if the share price stays below $1.90. I will consider selling off all my shares if its price hits above $2 in the short term because after the demerger, its new NAV is around $1.90 and $2 should be a fair value in the short term. If I think about why I invested in SCI in the first place, I particularly like its essential waste management and utilities business that I believe will has plenty of potential growth especially in developing countries such India and South East Asia and will be motivated to keep SCI for the long term.

I hope all SCI and SCM shareholders will make the wisest decisions for yourselves. Always think about why you bought the share in the first place. All the best! Thanks for reading.

Love & Peace,
Qiongster

Friday, June 05, 2020

Portfolio Rebalancing: Cut Starhub Buy Mapletree Industrial Trust

Mapletree Industrial Trust (MIT) will replace SPH in the Straits Times Index (STI) from 22 Jun 2020.


The STI is reflective of Singapore's economy and the 30 constituents are businesses with the largest market capitalization. It is evident that Reits have grown in stature and importance in Singapore as MIT will be the 6th Reit out of 30 companies in STI.

The STI reserve list comprises of Keppel DC Trust, Suntec Reit, NetLink Trust, Frasers L&C Trust and Keppel Reit. I am happy to own 4 of the 5 reserves.

It is time to realize that traditional old school corporations such as SPH, Sembcorp Industries, ComfortDelGro, Starhub, Singtel and SIA have all faced headwinds in their core businesses and seen declining profit margins and erosion of equity year after year.

The future is about technology and innovation. Apps, virtual reality, artificial intelligence, data analytics, digitalization. Data centres hosting IT infrastructure is the bedrock for the future. MIT, like a hybrid of Ascendas Reit and Keppel DC Trust, owns industrial properties as well as data centres on freehold land in the North America is the benchmark for the future.

It is with deep heart that I decided to cut my losses in Starhub and move on to MIT. I prefer stability, increasing dividend income and certainty in the future over possibility of declining earnings, reducing dividends and high capital expenditure on 5G infrastructure that will take decades to breakeven.

Mapletree Industrial Trust symbolises the future. Starhub represents the historic past and gone are the glory days. SPH is archaic. Nobody will want to watch Pay TV nor read hardcopy newspapers in the future. It is time to move on. The time is now or never. I scrambled to get on the boat. FOMO.


I believe all the exchange traded funds (ETF), hedge fund managers, portfolio managers are strategizing to remove SPH from their portfolios and scrambling to place huge bids to buy Mapletree Industrial Trust from today till 22 Jun. Their portfolios simply need to mimic STI and contain the 30 company shares. Though the valuation of MIT is not attractive, its share price will only rocket to the skies because there simply isn't enough shares for the funds to buy. With limited supply of shares, and oversupply of money, there will only be one outcome. $3 or $3.50. Pump and dump also does not matter. MIT will only grow its portfolio and pay increasing dividends and can be one of the best long term investments for the coming decade.

Thanks for reading!

Love & Peace,
Qiongster